Company Coverage
Advance Info Services (ADVANC TB): Operations Remain Stable, But Costs Expected To Increase Following Resumption Of Investment Plan
BUY (Maintained)
Current price:
Target price:
Upside:
Bt345.00
Bt415.00
20.3%
Analyst
Analyst
Sirithat Prasertwuti
Sirithat@uobkayhian.co.thHighlights
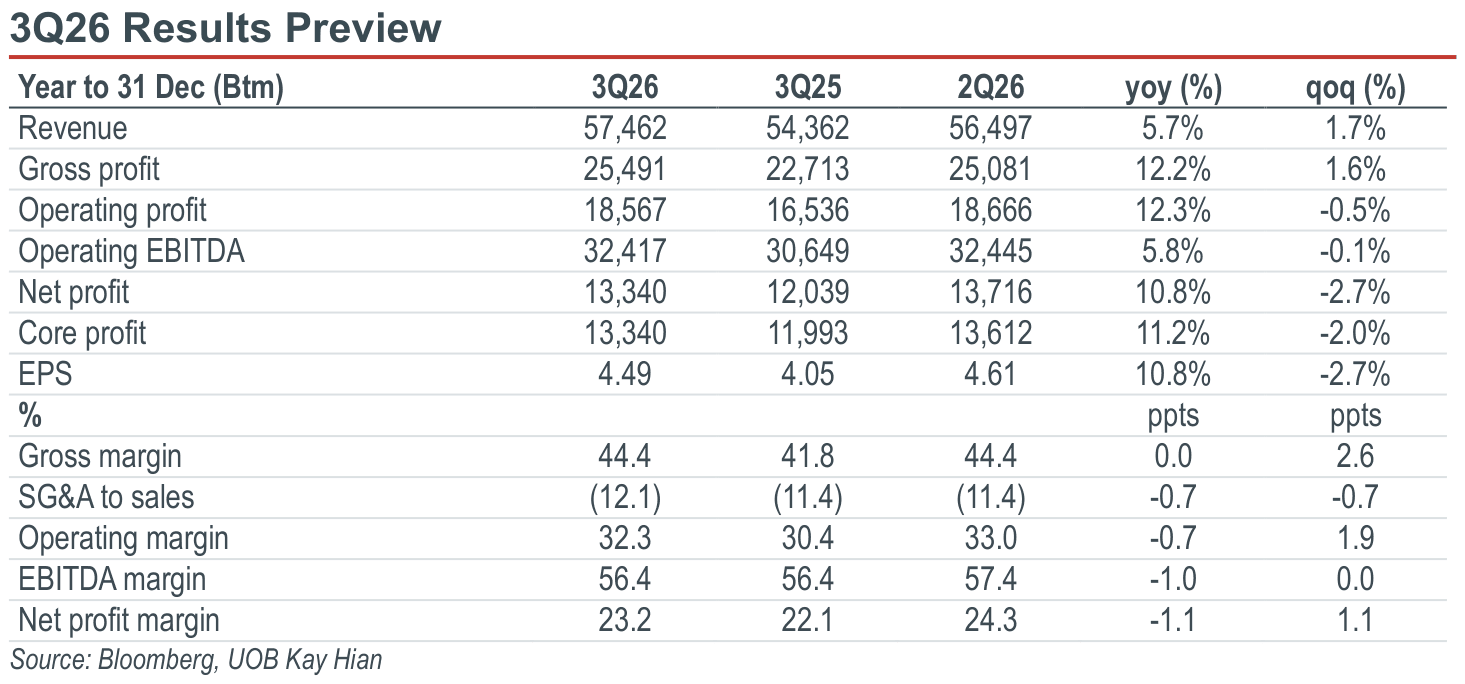
- We expect ADVANC to report a net profit of Bt13.34b (+11% yoy, -3% qoq).
- Operations remain stable, but costs are projected to rise due to IT investment, consistent with our previous outlook.
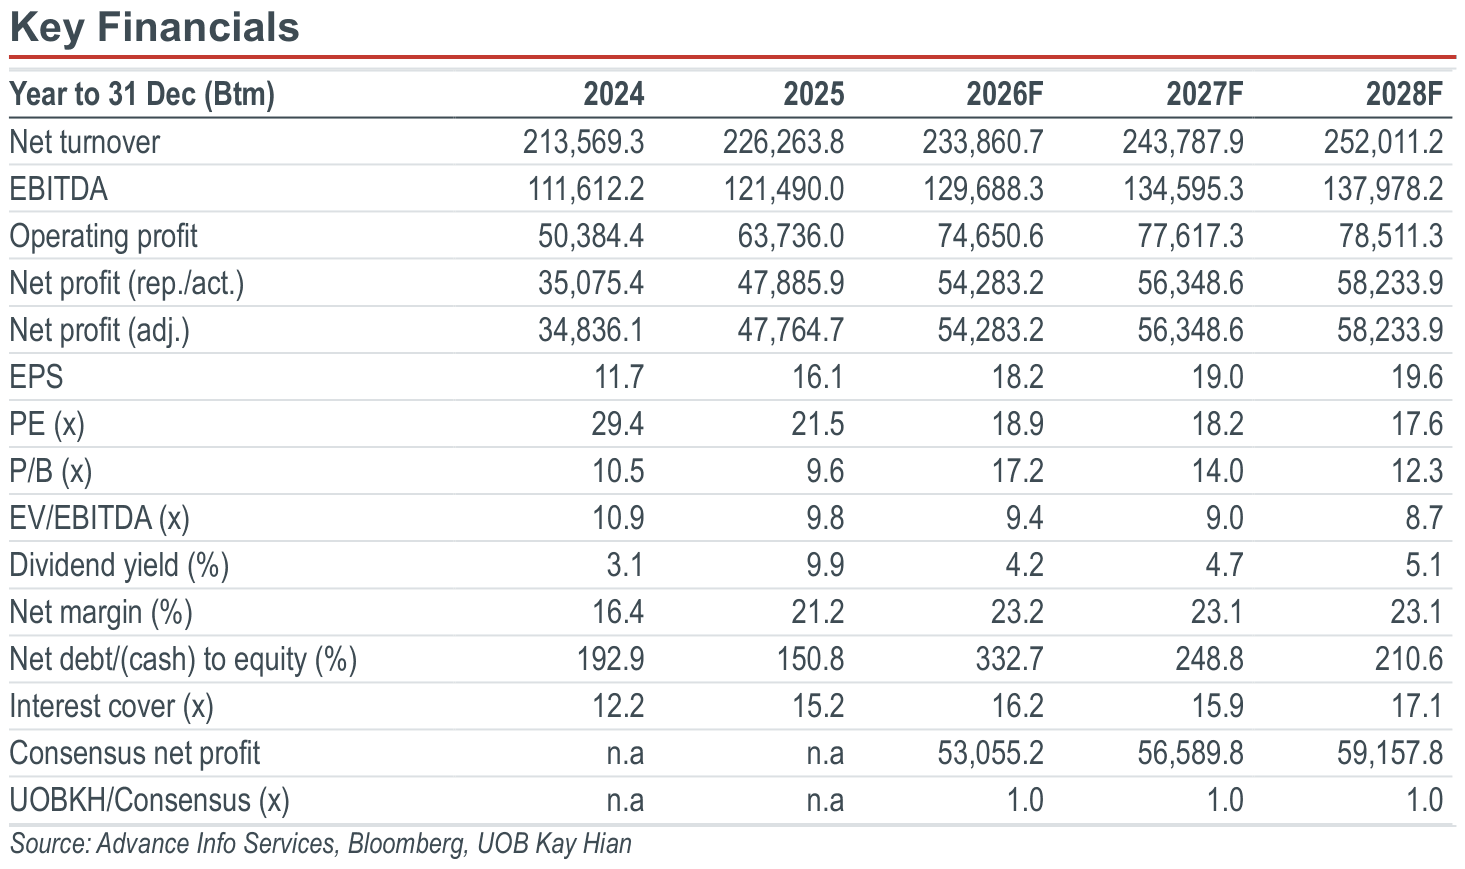
- Maintain BUY with a target price of Bt415.00. Any share price decline would offer a higher dividend yield and an attractive entry point, as we expect limited earnings downside.
Analysis
- Operations remain broadly stable, while costs are expected to rise in 2H26 following the resumption of IT investment. We expect ADVANC to report a net profit of Bt13.34b (+11% yoy, -2% qoq). Operations should remain stable, with core service revenue across the main segments remaining resilient at Bt45.83b (+5.1% yoy, +1% qoq). We foresee a stable gross margin of 44.4%. However, the qoq earnings decline is projected to reflect higher IT-related expenses (network depreciation and maintenance costs), as ADVANC resumes investment following cautious spending in 1H26 amid geopolitical uncertainty. This is consistent with last quarter’s outlook and plans to meet its 2026 capex guidance. Therefore, we expect SG&A expenses to increase slightly qoq by 12.1% in 3Q26 (vs 12.4%/11.4% in 1Q26-2Q26), although marketing expenses should be lower given the seasonal low period.
Highlights
- We expect ADVANC to report a net profit of Bt13.34b (+11% yoy, -3% qoq).
- Operations remain stable, but costs are projected to rise due to IT investment, consistent with our previous outlook.
- Maintain BUY with a target price of Bt415.00. Any share price decline would offer a higher dividend yield and an attractive entry point, as we expect limited earnings downside.
Analysis
- Operations remain broadly stable, while costs are expected to rise in 2H26 following the resumption of IT investment. We expect ADVANC to report a net profit of Bt13.34b (+11% yoy, -2% qoq). Operations should remain stable, with core service revenue across the main segments remaining resilient at Bt45.83b (+5.1% yoy, +1% qoq). We foresee a stable gross margin of 44.4%. However, the qoq earnings decline is projected to reflect higher IT-related expenses (network depreciation and maintenance costs), as ADVANC resumes investment following cautious spending in 1H26 amid geopolitical uncertainty. This is consistent with last quarter’s outlook and plans to meet its 2026 capex guidance. Therefore, we expect SG&A expenses to increase slightly qoq by 12.1% in 3Q26 (vs 12.4%/11.4% in 1Q26-2Q26), although marketing expenses should be lower given the seasonal low period.
BUY (Maintained)
Current price:
Target price:
Upside:
Bt345.00
Bt415.00
20.3%
Analyst
Analyst
Sirithat Prasertwuti
Sirithat@uobkayhian.co.thIMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


