Company Coverage
True Corporation (TRUE TB): Subscriber Numbers To Remain Healthy; Earnings Could Stay Positive For Seventh Consecutive Quarter
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Bt12.90
Bt16.50
27.9%
Bt15.70
Analyst
Analyst
Sirithat Prasertwuti
Sirithat@uobkh.co.thHighlights
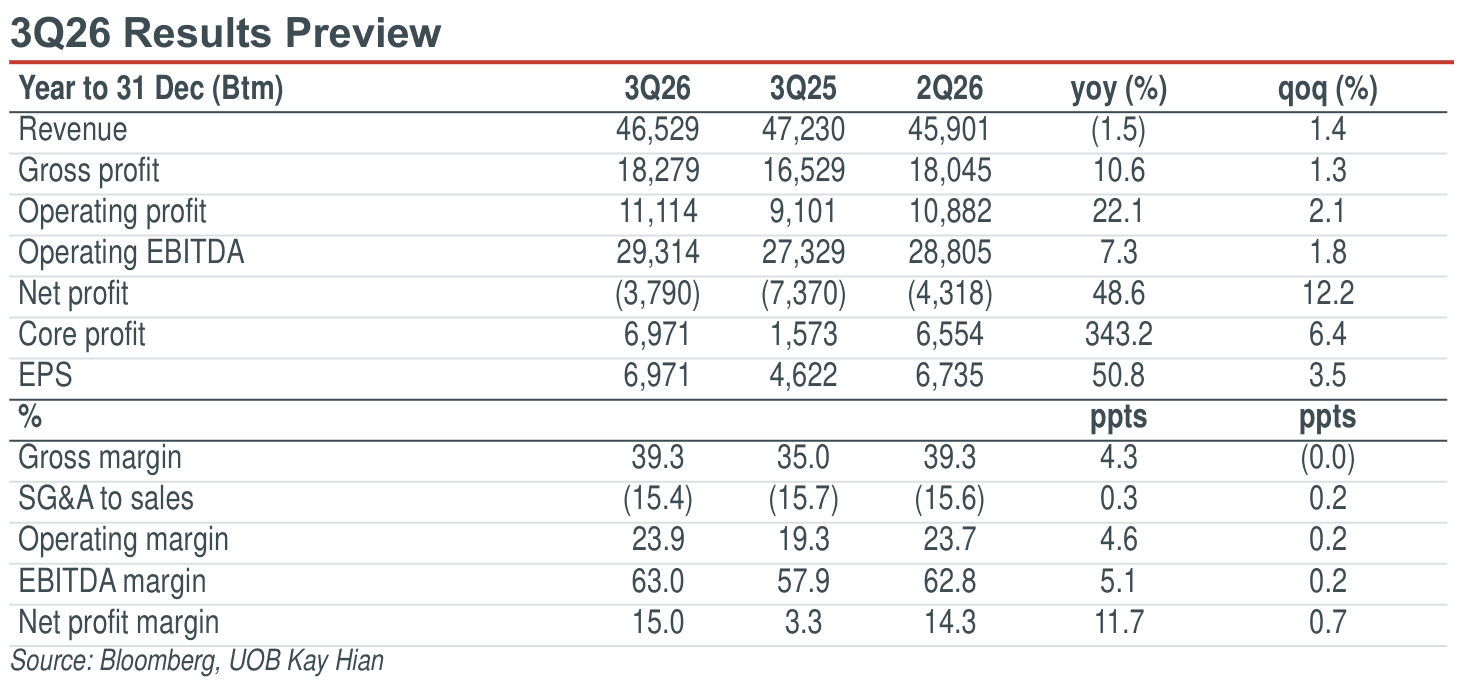
- We expect TRUE to report a 3Q26 net profit of Bt6.97b (+343% yoy, +6% qoq). The yoy increase should come from the low base last year due to a one-time network outage incident while qoq growth is forecast to come from several businesses remaining healthy.
- Earnings are expected to remain resilient, driven by continued growth in ARPU and subscribers qoq during the low season.
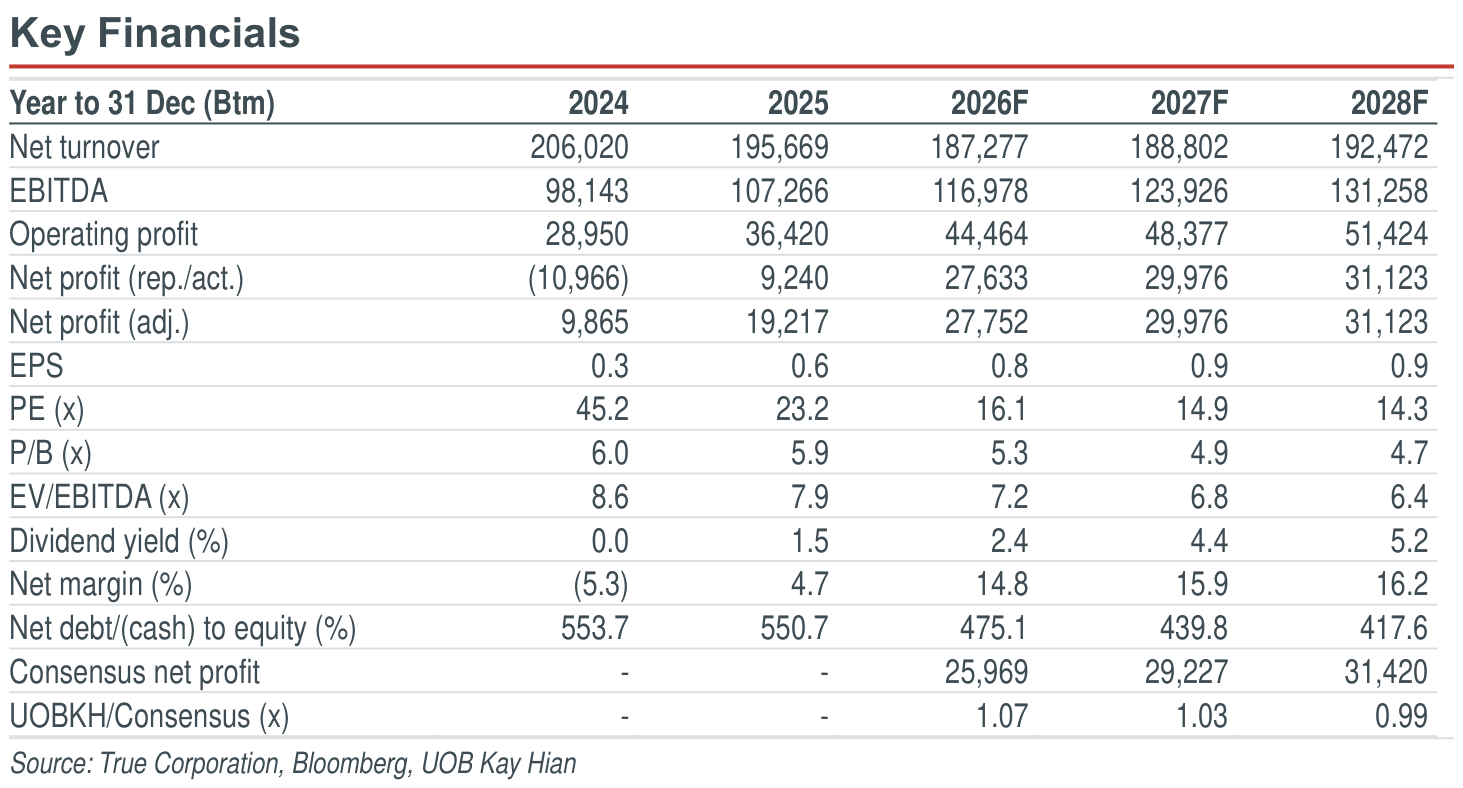
- We maintain BUY with a target price of Bt16.50.
Analysis
- Earnings should remain healthy, reaching an all-time high since the amalgamation. We expect True Corporation (TRUE) to report a net profit of Bt6.97b (+343% yoy, +6% qoq), marking an all-time high since the amalgamation. Earnings are projected to remain healthy, supported by continued growth across several key businesses and lower finance costs qoq. Sales could come in at Bt46.54b (-1% yoy, +1% qoq). However, we expect core service revenue to continue growing both yoy and qoq to Bt41.8b (+1.3% yoy, +1.0% qoq), driven by healthy performance in mobile, broadband, and TV, despite 3Q26 normally being a soft season, particularly for handset sales, as iPhone sales are likely to contribute mainly in 4Q26.
- Mobile and broadband is forecast to remain healthy yoy and qoq. We estimate that mobile and broadband revenue growth will remain healthy both yoy and qoq, while Pay TV is expected to rebound only qoq, as yoy growth remains pressured by fewer concerts compared with last year.
Highlights
- We expect TRUE to report a 3Q26 net profit of Bt6.97b (+343% yoy, +6% qoq). The yoy increase should come from the low base last year due to a one-time network outage incident while qoq growth is forecast to come from several businesses remaining healthy.
- Earnings are expected to remain resilient, driven by continued growth in ARPU and subscribers qoq during the low season.
- We maintain BUY with a target price of Bt16.50.
Analysis
- Earnings should remain healthy, reaching an all-time high since the amalgamation. We expect True Corporation (TRUE) to report a net profit of Bt6.97b (+343% yoy, +6% qoq), marking an all-time high since the amalgamation. Earnings are projected to remain healthy, supported by continued growth across several key businesses and lower finance costs qoq. Sales could come in at Bt46.54b (-1% yoy, +1% qoq). However, we expect core service revenue to continue growing both yoy and qoq to Bt41.8b (+1.3% yoy, +1.0% qoq), driven by healthy performance in mobile, broadband, and TV, despite 3Q26 normally being a soft season, particularly for handset sales, as iPhone sales are likely to contribute mainly in 4Q26.
- Mobile and broadband is forecast to remain healthy yoy and qoq. We estimate that mobile and broadband revenue growth will remain healthy both yoy and qoq, while Pay TV is expected to rebound only qoq, as yoy growth remains pressured by fewer concerts compared with last year.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Bt12.90
Bt16.50
27.9%
Bt15.70
Analyst
Analyst
Sirithat Prasertwuti
Sirithat@uobkh.co.thIMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

28 Sept 2026
Delta (Thailand) (DELTA TB) : 3Q26 Results Preview: Earnings Expected To Improve qoq, Driven By Higher Sales And Margins

19 Oct 2026
COM7 (COM7 TB): Earnings Expected To Surge In 3Q26

25 Sept 2026
i-Tail Corporation (ITC TB): 3Q26 Results Preview: Sustained Strong Sales Growth Momentum
Our latest research

21 Oct 2026
Airports of Thailand (AOT TB): Expect Robust Earnings In 4QFY26, Supported By PSC

21 Oct 2026
Bangkok Bank (BBL TB): 3Q26: Results In Line With Consensus; Showing Clean Loan Portfolio

20 Oct 2026