Company Coverage
OSOTSPA (OSP TB): Gradual Revenue Growth In 2027
BUY (Maintained)
Current price:
Target price:
Upside:
Bt18.75
Bt22.00
17.33%
Analyst
Highlights
- OSP reported 3Q26 core profit of Bt875m (+24.9% yoy, -20.5% qoq). International energy drink and personal care sales continued to show positive momentum, while gross profit margin remained resilient.
- We expect 4Q26 earnings to increase yoy but remain broadly flat qoq, supported by seasonal strength in personal care sales and a recovery in international markets, which should partially offset the impact of higher raw material costs.
- Maintain BUY with a target price of Bt22.00.
Analysis
- We attended OSOTSPA’s (OSP) analyst meeting after its 3Q26 results, and the tone of the meeting was neutral.
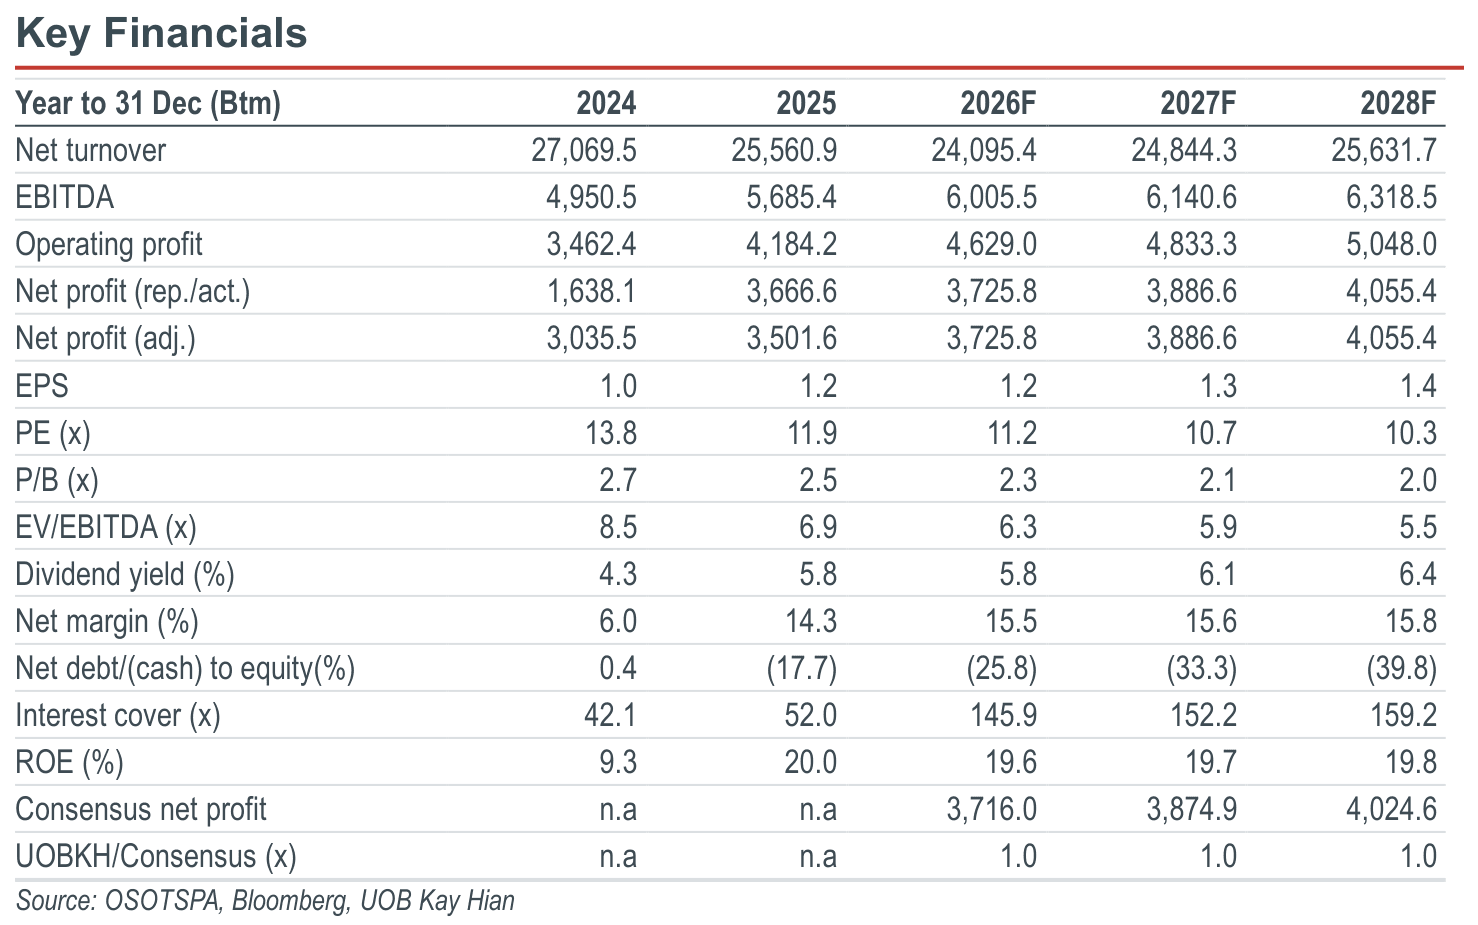
- 2027 revenue is expected to gradually increase, driven primarily by growth in the personal care segment. The company did not provide specific guidance for 2027 but indicated that revenue is expected to grow yoy. We maintain our forecast of 3% yoy revenue growth in 2027, primarily driven by the personal care segment, while the energy drink segment is expected to continue focusing on premiumisation. Nevertheless, we will continue to monitor competitive intensity in the Bt10 and premium segments, as well as the company's ability to expand its presence in the premium energy drink market.
- International business has shown signs of improvement. In the Myanmar market, progress in obtaining import licences has improved since 3Q26, although the recovery is expected to remain gradual. The company also plans to establish local production of glass-bottled energy drinks in Myanmar, which should help alleviate cost pressures and improve cost efficiency.
- 4Q26 earnings outlook. We expect 4Q26 earnings to increase yoy but remain broadly flat qoq, due to an anticipated decline in gross profit margin from higher raw material costs. Looking ahead, we expect profitability to improve as raw material costs gradually ease following the post-war normalisation. This should allow OSP to capture further benefits from cost restructuring, providing greater earnings visibility going forward.
Highlights
- OSP reported 3Q26 core profit of Bt875m (+24.9% yoy, -20.5% qoq). International energy drink and personal care sales continued to show positive momentum, while gross profit margin remained resilient.
- We expect 4Q26 earnings to increase yoy but remain broadly flat qoq, supported by seasonal strength in personal care sales and a recovery in international markets, which should partially offset the impact of higher raw material costs.
- Maintain BUY with a target price of Bt22.00.
Analysis
- We attended OSOTSPA’s (OSP) analyst meeting after its 3Q26 results, and the tone of the meeting was neutral.
- 2027 revenue is expected to gradually increase, driven primarily by growth in the personal care segment. The company did not provide specific guidance for 2027 but indicated that revenue is expected to grow yoy. We maintain our forecast of 3% yoy revenue growth in 2027, primarily driven by the personal care segment, while the energy drink segment is expected to continue focusing on premiumisation. Nevertheless, we will continue to monitor competitive intensity in the Bt10 and premium segments, as well as the company's ability to expand its presence in the premium energy drink market.
- International business has shown signs of improvement. In the Myanmar market, progress in obtaining import licences has improved since 3Q26, although the recovery is expected to remain gradual. The company also plans to establish local production of glass-bottled energy drinks in Myanmar, which should help alleviate cost pressures and improve cost efficiency.
- 4Q26 earnings outlook. We expect 4Q26 earnings to increase yoy but remain broadly flat qoq, due to an anticipated decline in gross profit margin from higher raw material costs. Looking ahead, we expect profitability to improve as raw material costs gradually ease following the post-war normalisation. This should allow OSP to capture further benefits from cost restructuring, providing greater earnings visibility going forward.
BUY (Maintained)
Current price:
Target price:
Upside:
Bt18.75
Bt22.00
17.33%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

21 Oct 2026
Osotspa (OSP TB): 3Q26 Results Preview: Margins Expected To Remain Resilient

2 Nov 2026
i-Tail Corporation (ITC TB) - 3Q26: Earnings In Line; Positive On Industry Growth

3 Nov 2026
Thai Union Group (TU TB) - 3Q26: Core Profit Beat Expectations; Core Operation To Improve Amid Higher Costs
Our latest research

20 Nov 2026
Asset World Corporation (AWC TB): Outlook Remains Robust Throughout The High Travel Season

19 Nov 2026
PTT (PTT TB): Geopolitical Tightness Now, Supply Glut Ahead – PTT Ramps Up Global Trading

19 Nov 2026