Company Coverage
Supalai (SPALI TB): Neutral View Amid Flood Impact; Remains Our Top Sector Pick
BUY (Maintained)
Current price:
Target price:
Upside:
Bt15.90
Bt17.50
+10.0%
Analyst
Analyst
Natthida Chuaysong
Highlights
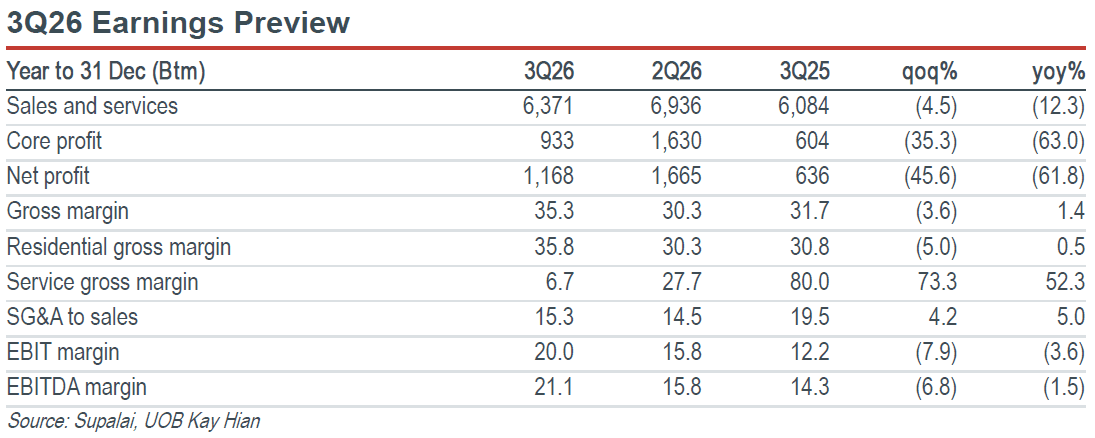
- We attended a market update meeting with management and came away with a neutral view. We expect SPALI to report 3Q26 net profit of Bt6.084b, down 12.3% qoq and 4.5% yoy. 3Q26 earnings are expected to be softer than previously guided, mainly due to flooding in Bangkok.
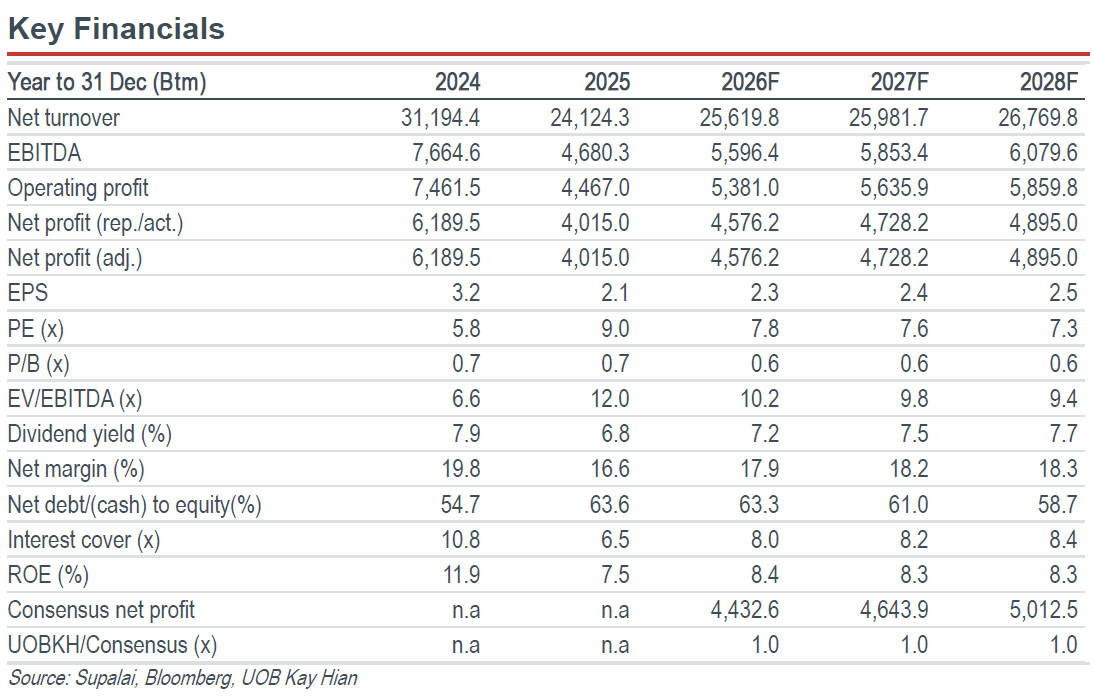
- We continue to like SPALI for its strong balance sheet and low leverage. While the Bangkok flood may weigh on property transfers in 3Q26, SPALI remains an attractive player in the property sector. We maintain our BUY recommendation with a target price of Bt17.50.
Analysis
- Neutral takeaways from management meeting. We attended a market update meeting with management and came away with a neutral view. We expect Supalai (SPALI) to report 3Q26 net profit of Bt6.084b (-12.3% qoq, -4.5% yoy), with total transfers expected at Bt5.974b (-12.5% qoq, -4.9% yoy). This is in line with 3Q26 presales of Bt5.571b, (vs Bt6.937b in 2Q26 and Bt6.012b in 1Q26).
Highlights
- We attended a market update meeting with management and came away with a neutral view. We expect SPALI to report 3Q26 net profit of Bt6.084b, down 12.3% qoq and 4.5% yoy. 3Q26 earnings are expected to be softer than previously guided, mainly due to flooding in Bangkok.
- We continue to like SPALI for its strong balance sheet and low leverage. While the Bangkok flood may weigh on property transfers in 3Q26, SPALI remains an attractive player in the property sector. We maintain our BUY recommendation with a target price of Bt17.50.
Analysis
- Neutral takeaways from management meeting. We attended a market update meeting with management and came away with a neutral view. We expect Supalai (SPALI) to report 3Q26 net profit of Bt6.084b (-12.3% qoq, -4.5% yoy), with total transfers expected at Bt5.974b (-12.5% qoq, -4.9% yoy). This is in line with 3Q26 presales of Bt5.571b, (vs Bt6.937b in 2Q26 and Bt6.012b in 1Q26).
BUY (Maintained)
Current price:
Target price:
Upside:
Bt15.90
Bt17.50
+10.0%
Analyst
Analyst
Natthida Chuaysong
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at the this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

12 Oct 2026
SCG Packaging (SCGP TB): 3Q26 Earnings Remain Strong Despite Higher RCP Costs

15 Oct 2026
Tisco Financial Group (TISCO TB): 3Q26: Results In Line; Clean Asset Quality With A High Buffer

5 Oct 2026
Central Pattana (CPN TB) - Central Khonkaen Campus: A New Lifestyle Destination In Isan
Our latest research

21 Oct 2026
Airports of Thailand (AOT TB): Expect Robust Earnings In 4QFY26, Supported By PSC

21 Oct 2026
Bangkok Bank (BBL TB): 3Q26: Results In Line With Consensus; Showing Clean Loan Portfolio

20 Oct 2026