Company Coverage
MR. D.I.Y. Thailand (MRDIYT TB): 2Q26: Results In Line; Strong Margin Expansion
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Bt9.85
Bt11.00
+11.68%
-
Analyst
Highlights
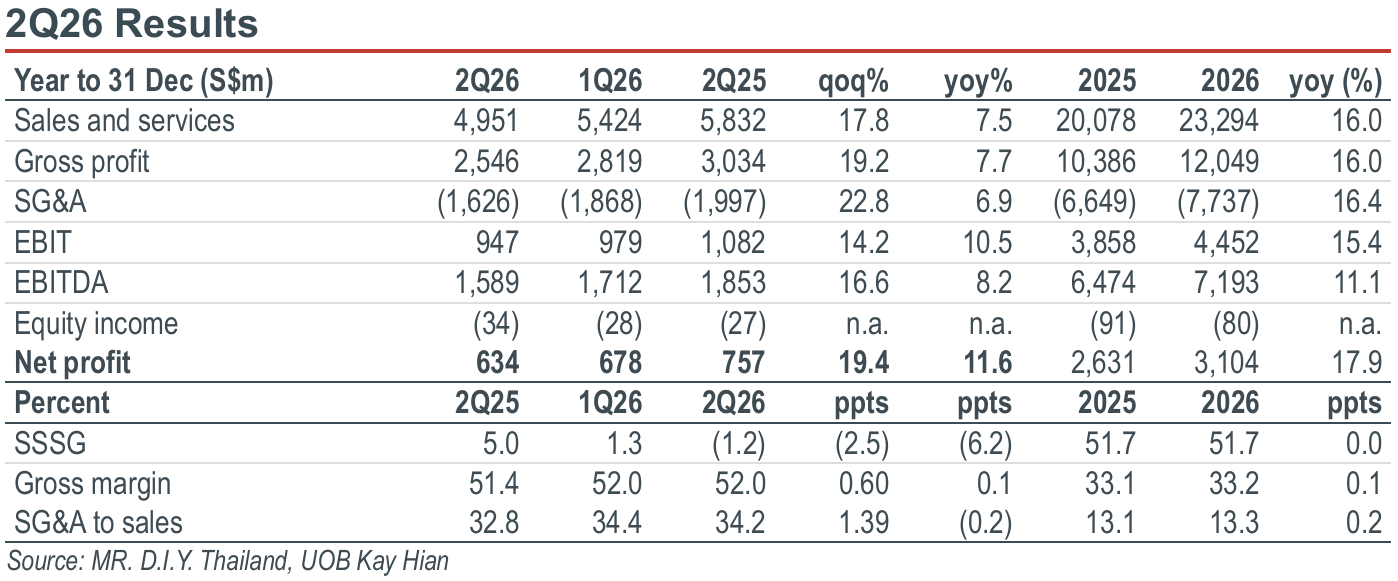
MRDIYT reported 2Q26 net profit of Bt757m (+19% yoy, +12% qoq), in line with our and market expectations.
Earnings growth is expected to remain positive throughout 2H26, driven by continued store expansion.
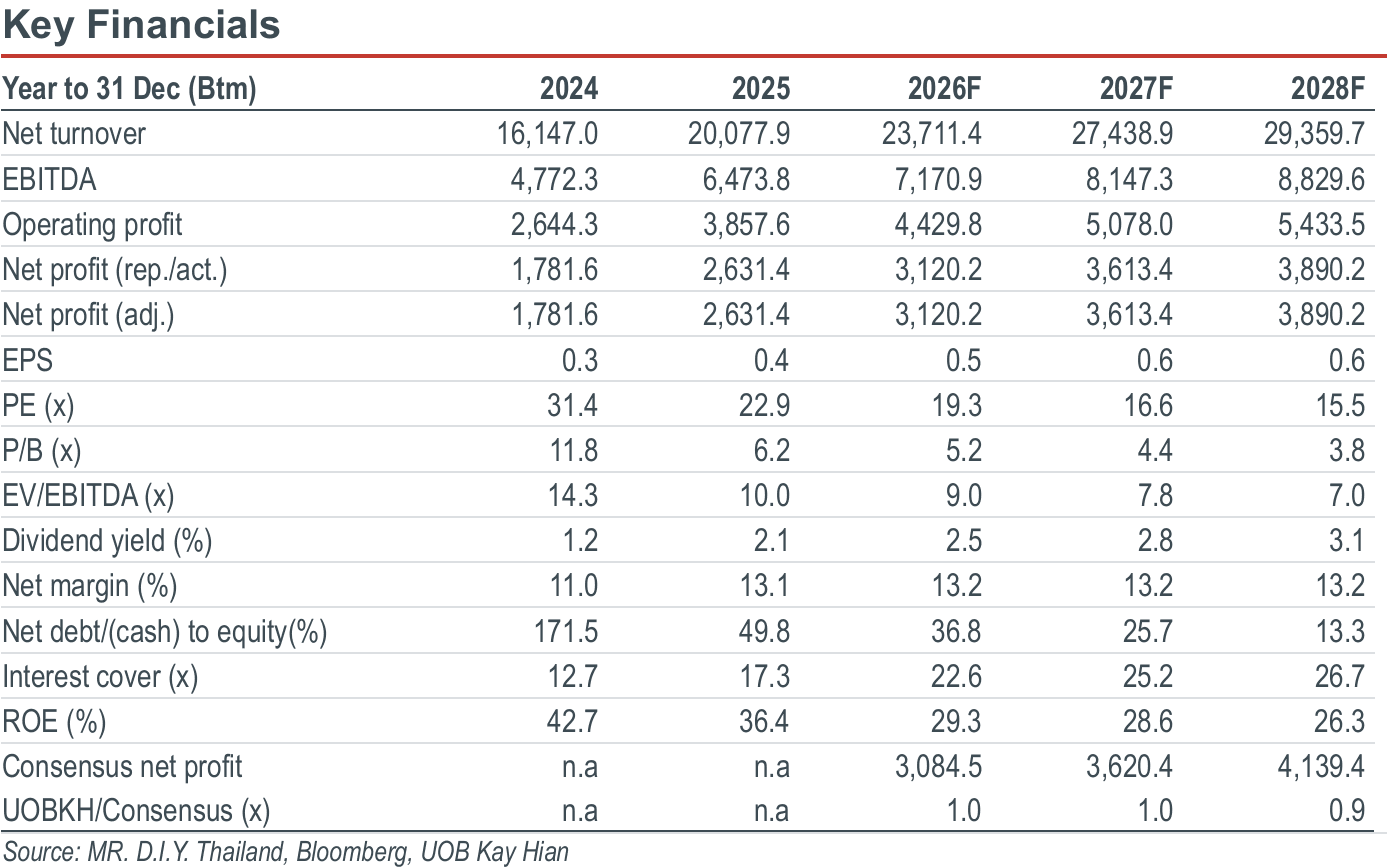
Maintain BUY with a target price of Bt11.00, or 12-month forward PE of 20x.
Analysis
- Results in line. MR. D.I.Y. Thailand (MRDIYT) reported 2Q26 net profit of Bt757m, rising 19% yoy and 12% qoq, in line with our and consensus expectations, supported by revenue growth, higher gross margin, increased other income, and lower losses from KKV. 2Q26 SSSG was -1.2% yoy, mainly due to a high base in 2Q25, which benefitted from tax incentives for school supplies. The impact of the Thai Help Thai Plus copayment scheme was neutral for MRDIYT, with sales performing well in the first two weeks of Jun 26 before slowing thereafter. Gross margin in 2Q26 expanded by 60bps to 52.0%, reaching the upper end of the company’s full-year target, with no impact from higher costs seen yet. SG&A-to-sales increased 139 bps to 34.2%, driven by store expansion and weaker SSSG. Losses from KKV are expected to decline to Bt28m.
Essential
Store expansion to remain the key earnings driver. Looking ahead, we expect 3Q26 earnings to continue growing yoy, although growth should moderate due to a high base in the previous year. SSSG in the first two weeks of July recovered to slightly positive yoy, with momentum improving from June. Store expansion remains on track, with the company having secured locations and construction plans for 95% of its 2026 target of 210 new stores. Overall, we expect earnings growth to remain positive throughout 2H26, driven by continued store expansion.
Highlights
MRDIYT reported 2Q26 net profit of Bt757m (+19% yoy, +12% qoq), in line with our and market expectations.
Earnings growth is expected to remain positive throughout 2H26, driven by continued store expansion.
Maintain BUY with a target price of Bt11.00, or 12-month forward PE of 20x.
Analysis
- Results in line. MR. D.I.Y. Thailand (MRDIYT) reported 2Q26 net profit of Bt757m, rising 19% yoy and 12% qoq, in line with our and consensus expectations, supported by revenue growth, higher gross margin, increased other income, and lower losses from KKV. 2Q26 SSSG was -1.2% yoy, mainly due to a high base in 2Q25, which benefitted from tax incentives for school supplies. The impact of the Thai Help Thai Plus copayment scheme was neutral for MRDIYT, with sales performing well in the first two weeks of Jun 26 before slowing thereafter. Gross margin in 2Q26 expanded by 60bps to 52.0%, reaching the upper end of the company’s full-year target, with no impact from higher costs seen yet. SG&A-to-sales increased 139 bps to 34.2%, driven by store expansion and weaker SSSG. Losses from KKV are expected to decline to Bt28m.
Essential
Store expansion to remain the key earnings driver. Looking ahead, we expect 3Q26 earnings to continue growing yoy, although growth should moderate due to a high base in the previous year. SSSG in the first two weeks of July recovered to slightly positive yoy, with momentum improving from June. Store expansion remains on track, with the company having secured locations and construction plans for 95% of its 2026 target of 210 new stores. Overall, we expect earnings growth to remain positive throughout 2H26, driven by continued store expansion.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Bt9.85
Bt11.00
+11.68%
-
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at the following link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

8 Sept 2026
Property: Sector Passes Its 1H26 Trough; Transfer Momentum Expected To Accelerate Towards Year-end

15 Sept 2026
Industrial Estate: Riding Thailand’s Tech Investment Cycle

28 Sept 2026
Delta (Thailand) (DELTA TB) : 3Q26 Results Preview: Earnings Expected To Improve qoq, Driven By Higher Sales And Margins
Our latest research

21 Oct 2026
Airports of Thailand (AOT TB): Expect Robust Earnings In 4QFY26, Supported By PSC

21 Oct 2026
Bangkok Bank (BBL TB): 3Q26: Results In Line With Consensus; Showing Clean Loan Portfolio

21 Oct 2026