Company Coverage
Minor International (MINT TB): Strong Operations In 4Q26 But No Improvement In Interest Savings
HOLD (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Bt22.00
Bt21.00
-4.5%
Bt19.50
Analyst
Analyst
Nonpawit Vathanadachakul
Highlights
- We attended MINT’s analyst meeting to review its 3Q26 results and the tone was neutral.
- The operation outlook for 4Q26 remains strong, but the progress of asset rotation will be gradual and will be completed by 2027.
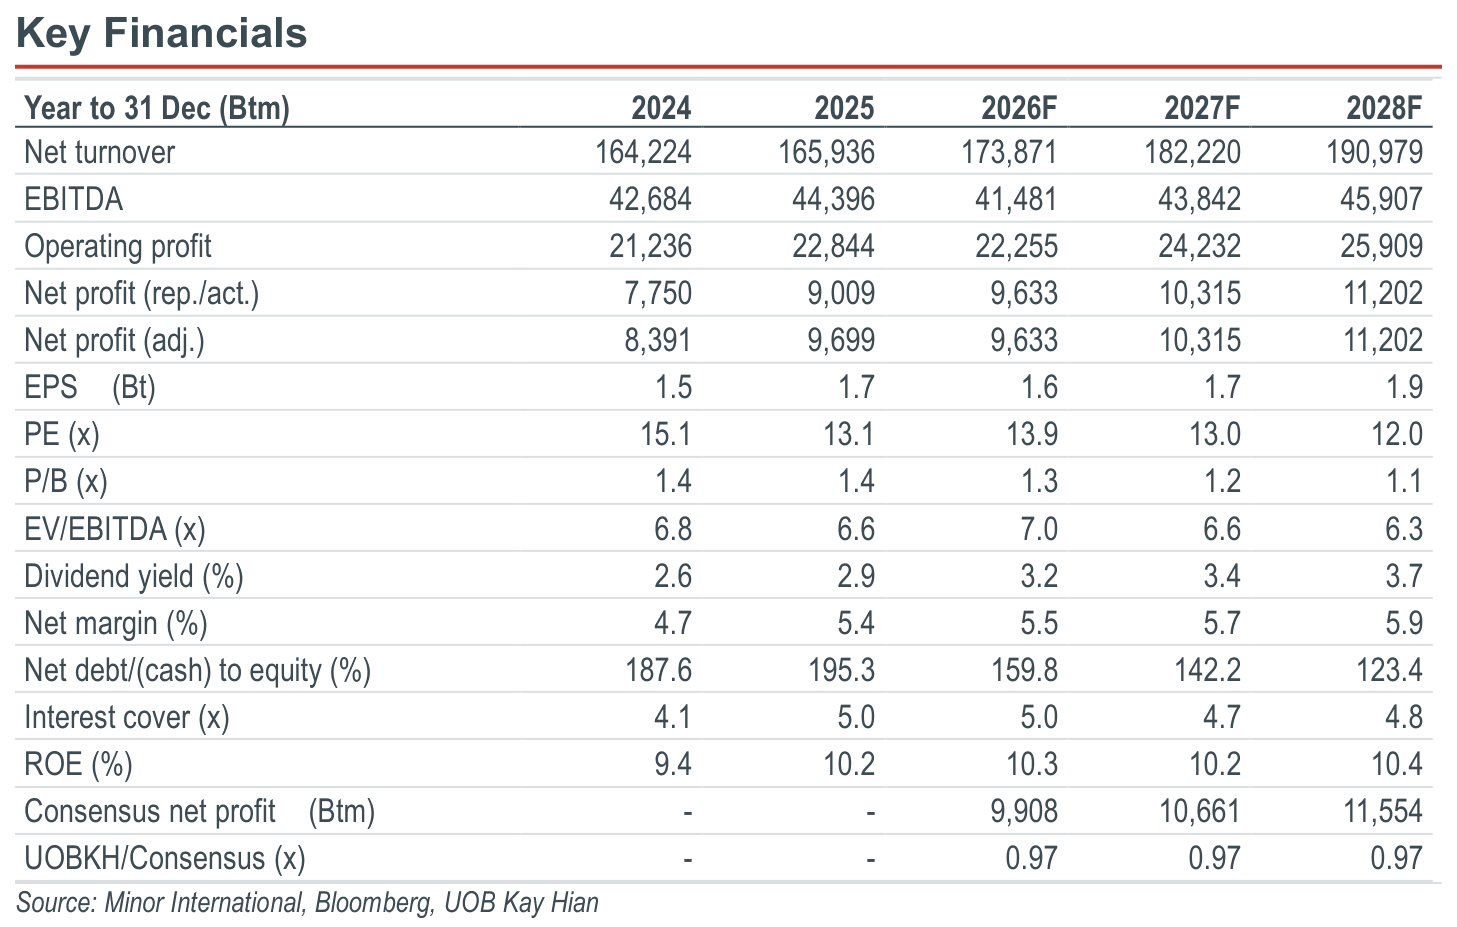
- We remain cautious on MINT as its interest expense remains high and the interest uptrend in Europe will be detrimental to MINT’s earnings outlook. Maintain HOLD with a target price of Bt21.00. (previously Bt19.50).
Analysis
- Neutral tone during analyst meeting. We attended Minor International’s (MINT) analyst meeting to review its 3Q26 results, and the tone was neutral.
- Early view for 2027 and 4Q26 outlook. MINT is still preparing its targets for next year. Management has provided a sneak peek into 2027. For its hotel business, management targets around low-mid single-digit RevPar growth yoy from Europe hotels and 8-10% RevPar growth yoy from hotels in Thailand. Meanwhile, it targets same-store-sales growth (SSSG) of +2% for its food business for 2027. For 4Q26, the outlook remains positive for hotels, with bookings in most locations indicating positive RevPar yoy. However, RevPar growth in Thailand at mid-single digit yoy remains subtle and weak despite several events and post renovation period. Meanwhile, the food business is performing well, having achieved 7% SSSG in Oct 26. The momentum has carried on into Nov 26 with a 6% SSSG for the first half of the month. This is a good build-up to the festive period when consumption demand will remain high.
- Prioritising margin protection. MINT’s key goal in 4Q26 is protecting its operating margin. The company is actively trimming operating costs for both the hotel and food businesses. MINT has implemented AI initiatives and carried out technology transformation to increase its operational efficiency. Moreover, the asset-light expansions could enhance margins of both hotel and food businesses. However, MINT’s key headwind remains the high interest expense from its loans. Even if the company is able to maintain its margins, the upward trend in interest expense will be detrimental to its earnings growth. We see that the current environment is not favourable for MINT’s earnings outlook.
Highlights
- We attended MINT’s analyst meeting to review its 3Q26 results and the tone was neutral.
- The operation outlook for 4Q26 remains strong, but the progress of asset rotation will be gradual and will be completed by 2027.
- We remain cautious on MINT as its interest expense remains high and the interest uptrend in Europe will be detrimental to MINT’s earnings outlook. Maintain HOLD with a target price of Bt21.00. (previously Bt19.50).
Analysis
- Neutral tone during analyst meeting. We attended Minor International’s (MINT) analyst meeting to review its 3Q26 results, and the tone was neutral.
- Early view for 2027 and 4Q26 outlook. MINT is still preparing its targets for next year. Management has provided a sneak peek into 2027. For its hotel business, management targets around low-mid single-digit RevPar growth yoy from Europe hotels and 8-10% RevPar growth yoy from hotels in Thailand. Meanwhile, it targets same-store-sales growth (SSSG) of +2% for its food business for 2027. For 4Q26, the outlook remains positive for hotels, with bookings in most locations indicating positive RevPar yoy. However, RevPar growth in Thailand at mid-single digit yoy remains subtle and weak despite several events and post renovation period. Meanwhile, the food business is performing well, having achieved 7% SSSG in Oct 26. The momentum has carried on into Nov 26 with a 6% SSSG for the first half of the month. This is a good build-up to the festive period when consumption demand will remain high.
- Prioritising margin protection. MINT’s key goal in 4Q26 is protecting its operating margin. The company is actively trimming operating costs for both the hotel and food businesses. MINT has implemented AI initiatives and carried out technology transformation to increase its operational efficiency. Moreover, the asset-light expansions could enhance margins of both hotel and food businesses. However, MINT’s key headwind remains the high interest expense from its loans. Even if the company is able to maintain its margins, the upward trend in interest expense will be detrimental to its earnings growth. We see that the current environment is not favourable for MINT’s earnings outlook.
HOLD (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Bt22.00
Bt21.00
-4.5%
Bt19.50
Analyst
Analyst
Nonpawit Vathanadachakul
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

30 Oct 2026
Minor International (MINT TB): Soft Core Growth Expected In 3Q26 Due To Margin Weakness

20 Nov 2026
Asset World Corporation (AWC TB): Outlook Remains Robust Throughout The High Travel Season

30 Oct 2026
Central Plaza Hotel (CENTEL TB): Expect Robust 3Q26 Earnings, Supported By Strong RevPar Growth
Our latest research
20 Nov 2026
Asset World Corporation (AWC TB): Outlook Remains Robust Throughout The High Travel Season

19 Nov 2026
PTT (PTT TB): Geopolitical Tightness Now, Supply Glut Ahead – PTT Ramps Up Global Trading

19 Nov 2026