Analyst
Analyst
Krit Tanarattananon
krit@uobkh.co.thAnalyst
Thailand Research Team
research@uobkh.co.thAnalyst
Natthida Chuaysong
Highlights
- 3Q26 earnings are in line with expectations, with earnings forecasts for 2026F and 2027F remaining largely unchanged.
- We maintain our 2028 SET target at 1,818pt. using an earnings yield gap (EYG) approach to better capture the relative attractiveness of equities against fixed-income assets.
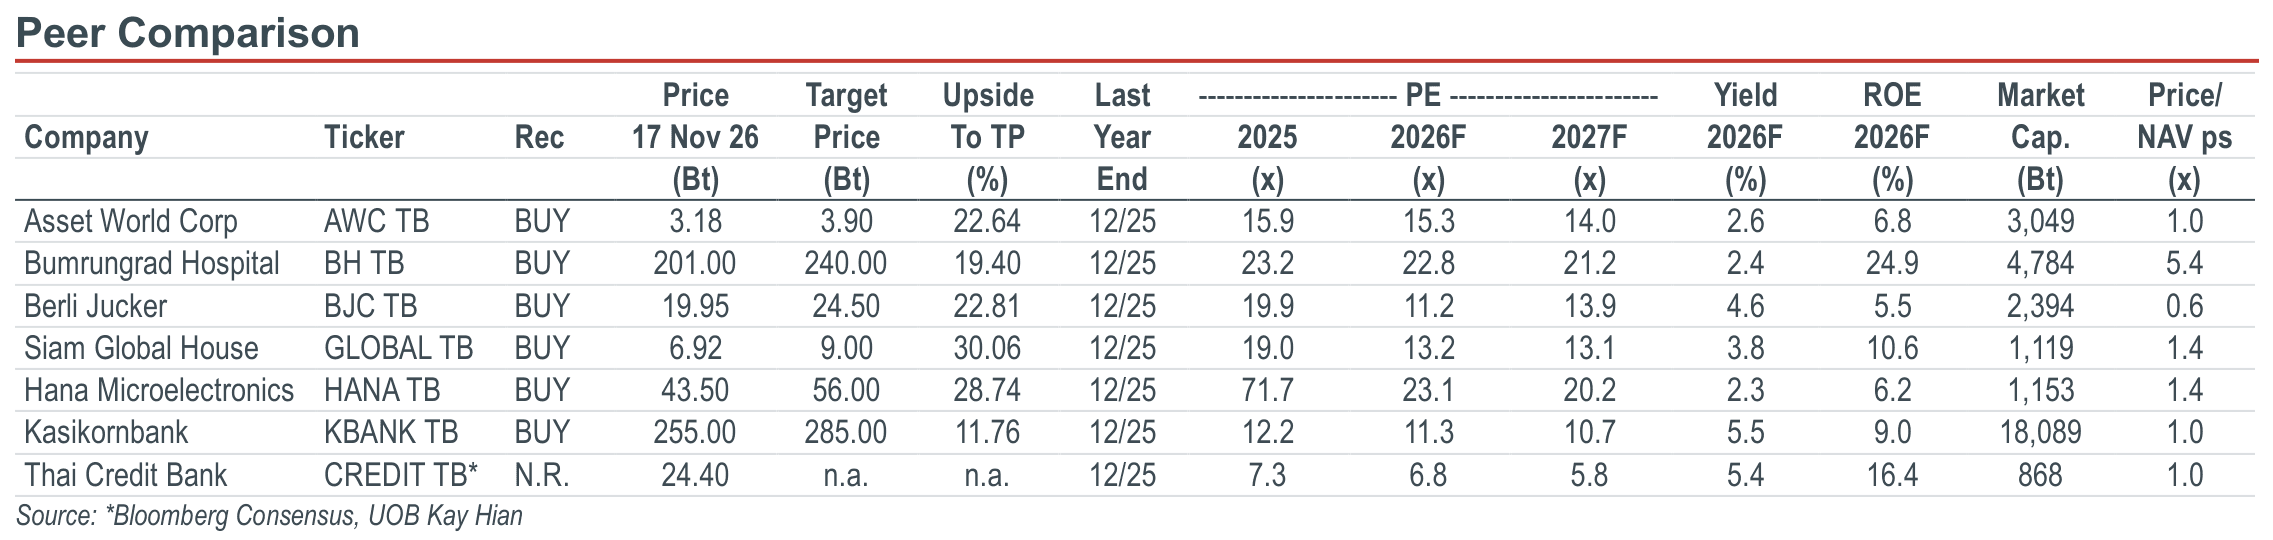
- Our top picks are AWC, BH, BJC, CREDIT, GLOBAL, HANA, and KBANK.
What’s New
- 3Q26 market recap: Despite expectations of an earnings recovery, market sentiment remained under pressure from rising global bond yields and external uncertainties, which weighed on equity prices. Against this backdrop, our 3Q26 pick, comprising AOT, BJC, CENTEL, DELTA, GUNKUL, PR9, and PTTGC, delivered a net return of -2.5%, outperforming the benchmark's -8.4% return by 5.9ppt.
- Good earnings but momentum stalled. In 3Q26, net profit came in at Bt298,682 (+43.3% yoy, -5.8% qoq). This is in line with expectations, with four sectors reporting higher-than-expected earnings (vs 11 sectors in 2Q26 and 13 sectors in 1Q26). Eight sectors reported lower-than-expected earnings. Positive surges in terms of value came from the utilities (Bt4.1416b) and consumer staples sectors (Bt3.155b). Negative surges in terms of value came from electronics (-Bt9.077b) and transportation sectors (-Bt1.024b).
- No revision to total earnings forecast for 2026. 3Q26 earnings are in line with expectations, with earnings forecasts for 2026F and 2027F remaining largely unchanged. However, earnings revisions varied across sectors, with downward revisions in electronics (-3.5ppt) from raw material shortages, property (-3.2ppt) from pressured gross margin and banking (-1.1ppt). These downward revisions were offset by an upward revision in the utilities sector, up by 11.5ppt, Overall, earnings revisions for the market remained flat for 2027F.
Looking Ahead
- 4Q26 outlook. We expect 4Q26 earnings to grow yoy, while overall risks are expected to remain elevated amid macroeconomic uncertainty stemming from potential global interest rate hikes and policy changes following the US midterm elections. Meanwhile, more stable oil prices could affect earnings growth in the energy sector.
- Key risks to monitor: Energy prices, AI & data centre progress, rising global yield.
Highlights
- 3Q26 earnings are in line with expectations, with earnings forecasts for 2026F and 2027F remaining largely unchanged.
- We maintain our 2028 SET target at 1,818pt. using an earnings yield gap (EYG) approach to better capture the relative attractiveness of equities against fixed-income assets.
- Our top picks are AWC, BH, BJC, CREDIT, GLOBAL, HANA, and KBANK.
What’s New
- 3Q26 market recap: Despite expectations of an earnings recovery, market sentiment remained under pressure from rising global bond yields and external uncertainties, which weighed on equity prices. Against this backdrop, our 3Q26 pick, comprising AOT, BJC, CENTEL, DELTA, GUNKUL, PR9, and PTTGC, delivered a net return of -2.5%, outperforming the benchmark's -8.4% return by 5.9ppt.
- Good earnings but momentum stalled. In 3Q26, net profit came in at Bt298,682 (+43.3% yoy, -5.8% qoq). This is in line with expectations, with four sectors reporting higher-than-expected earnings (vs 11 sectors in 2Q26 and 13 sectors in 1Q26). Eight sectors reported lower-than-expected earnings. Positive surges in terms of value came from the utilities (Bt4.1416b) and consumer staples sectors (Bt3.155b). Negative surges in terms of value came from electronics (-Bt9.077b) and transportation sectors (-Bt1.024b).
- No revision to total earnings forecast for 2026. 3Q26 earnings are in line with expectations, with earnings forecasts for 2026F and 2027F remaining largely unchanged. However, earnings revisions varied across sectors, with downward revisions in electronics (-3.5ppt) from raw material shortages, property (-3.2ppt) from pressured gross margin and banking (-1.1ppt). These downward revisions were offset by an upward revision in the utilities sector, up by 11.5ppt, Overall, earnings revisions for the market remained flat for 2027F.
Looking Ahead
- 4Q26 outlook. We expect 4Q26 earnings to grow yoy, while overall risks are expected to remain elevated amid macroeconomic uncertainty stemming from potential global interest rate hikes and policy changes following the US midterm elections. Meanwhile, more stable oil prices could affect earnings growth in the energy sector.
- Key risks to monitor: Energy prices, AI & data centre progress, rising global yield.
Analyst
Analyst
Krit Tanarattananon
krit@uobkh.co.thAnalyst
Thailand Research Team
research@uobkh.co.thAnalyst
Natthida Chuaysong
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


