Company Coverage
Tidlor Holdings Pcl (TIDLOR TB) - 3Q26 Results Preview: Loan Growth To Continue While Provisions Expected To Rise From Flooding
BUY (Maintained)
Current price:
Target price:
Upside:
Bt16.50
Bt25.00
+51.52%
Analyst
Analyst
Panjarat Thaweesriprasert
Highlights
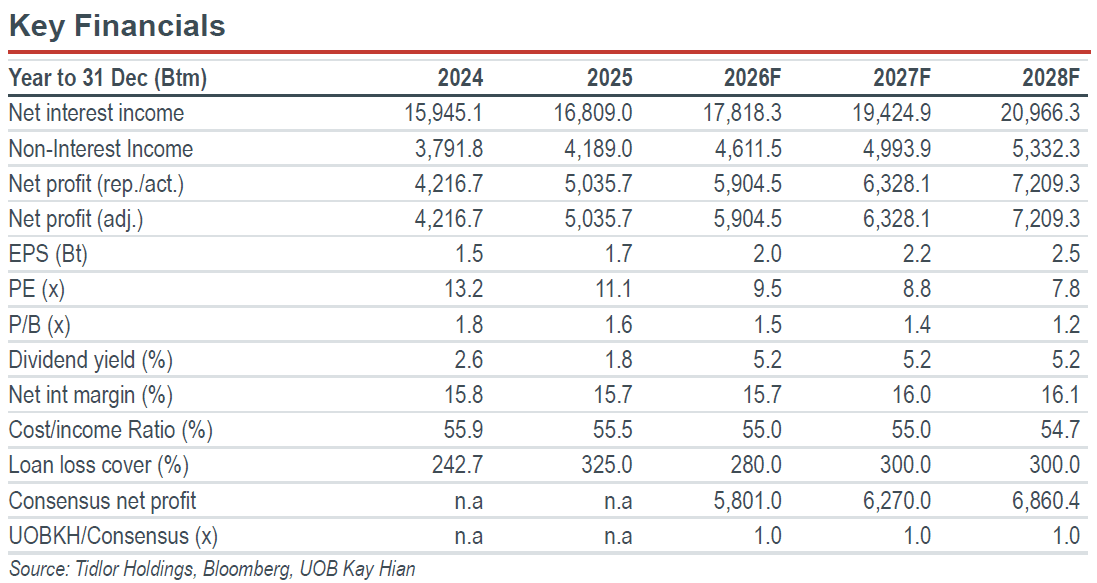
- We expect TIDLOR to post a 3Q26 net profit of Bt1.42b, up 0.9% yoy but down 7% qoq.
- 3Q26 provisions are projected at Bt814m, up 38% yoy and 43% qoq mainly due to the impact of Bangkok flooding.
- Maintain BUY with an unchanged target price of Bt25.00.
Analysis
- 3Q26 net profit to stable yoy and decline qoq. We expect TIDLOR Holdings (TIDLOR) to report a 3Q26 net profit of Bt1.42b, improving slightly by 0.9% yoy but declining 7% qoq. Excluding provisions, pre-provision operating profit should stand at Bt2.23b, increasing 12% yoy and 6% qoq.
- Loan portfolios to expand yoy and qoq. We forecast the loan portfolio growing to Bt115.6b, up 7.7% yoy and 2.7% qoq, supported by title loans, while the hire-purchase portfolio is projected to remain stable given prudent and disciplined underwriting and selective growth. We expect truck loan growth to remain under pressure, given crude oil prices above US$100/bbl and the 2027 budget disbursement only starting to accelerate from 29 September. Overall, we reiterate our 2026 loan growth forecast of 7%, in line with the company’s 2026 target of 5-10%.
- Non-II to continue growing yoy and qoq. TIDLOR’s non-interest income is expected to reach Bt1.18b, up 15.8% yoy and 12.5% qoq, driven by growing market share across both online and offline channels, along with cross-selling of personal accident, fire, and travel insurance. Management also sees further room for growth, although the average premium per policy is lower given the current economic conditions.
- Provisions to increase yoy and qoq. We expect TIDLOR’s provisions for 3Q26 to stand at Bt814m, up 38% yoy and 43% qoq, partly due to the impact of flooding in Bangkok and Vicinity. TIDLOR’s branches in Bangkok and surrounding areas account for approximately 28% of its total branches. We foresee the company building a provision cushion against potential flood-related losses, similar to what it did in 4Q25 when it set aside management overlay for flooding in the southern region. As a result, we estimate credit cost at 286bp, up 80bp from 2Q26.
Highlights
- We expect TIDLOR to post a 3Q26 net profit of Bt1.42b, up 0.9% yoy but down 7% qoq.
- 3Q26 provisions are projected at Bt814m, up 38% yoy and 43% qoq mainly due to the impact of Bangkok flooding.
- Maintain BUY with an unchanged target price of Bt25.00.
Analysis
- 3Q26 net profit to stable yoy and decline qoq. We expect TIDLOR Holdings (TIDLOR) to report a 3Q26 net profit of Bt1.42b, improving slightly by 0.9% yoy but declining 7% qoq. Excluding provisions, pre-provision operating profit should stand at Bt2.23b, increasing 12% yoy and 6% qoq.
- Loan portfolios to expand yoy and qoq. We forecast the loan portfolio growing to Bt115.6b, up 7.7% yoy and 2.7% qoq, supported by title loans, while the hire-purchase portfolio is projected to remain stable given prudent and disciplined underwriting and selective growth. We expect truck loan growth to remain under pressure, given crude oil prices above US$100/bbl and the 2027 budget disbursement only starting to accelerate from 29 September. Overall, we reiterate our 2026 loan growth forecast of 7%, in line with the company’s 2026 target of 5-10%.
- Non-II to continue growing yoy and qoq. TIDLOR’s non-interest income is expected to reach Bt1.18b, up 15.8% yoy and 12.5% qoq, driven by growing market share across both online and offline channels, along with cross-selling of personal accident, fire, and travel insurance. Management also sees further room for growth, although the average premium per policy is lower given the current economic conditions.
- Provisions to increase yoy and qoq. We expect TIDLOR’s provisions for 3Q26 to stand at Bt814m, up 38% yoy and 43% qoq, partly due to the impact of flooding in Bangkok and Vicinity. TIDLOR’s branches in Bangkok and surrounding areas account for approximately 28% of its total branches. We foresee the company building a provision cushion against potential flood-related losses, similar to what it did in 4Q25 when it set aside management overlay for flooding in the southern region. As a result, we estimate credit cost at 286bp, up 80bp from 2Q26.
BUY (Maintained)
Current price:
Target price:
Upside:
Bt16.50
Bt25.00
+51.52%
Analyst
Analyst
Panjarat Thaweesriprasert
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


