Company Coverage
KCE (Thailand) (KCE TB): 3Q26 Earnings Expected To Be Strong, Driven By Higher Volume And PCB Prices, But We Are More Cautious On Valuation
HOLD (Downgraded)
Current price:
Target price:
Upside:
Previous TP :
Bt74.75
Bt80.00
7.02%
Bt65.00
Analyst
Analyst
Sirithat Prasertwuti
Sirithat@uobkh.co.thHighlights
- We expect KCE to post strong earnings of Bt507m (+71% yoy, +84% qoq), driven by strong sales volume and higher PCB prices.
- Humanoid robot projects offer long-term diversification potential, but are unlikely to contribute meaningfully to earnings over the next several years in our forecasts.
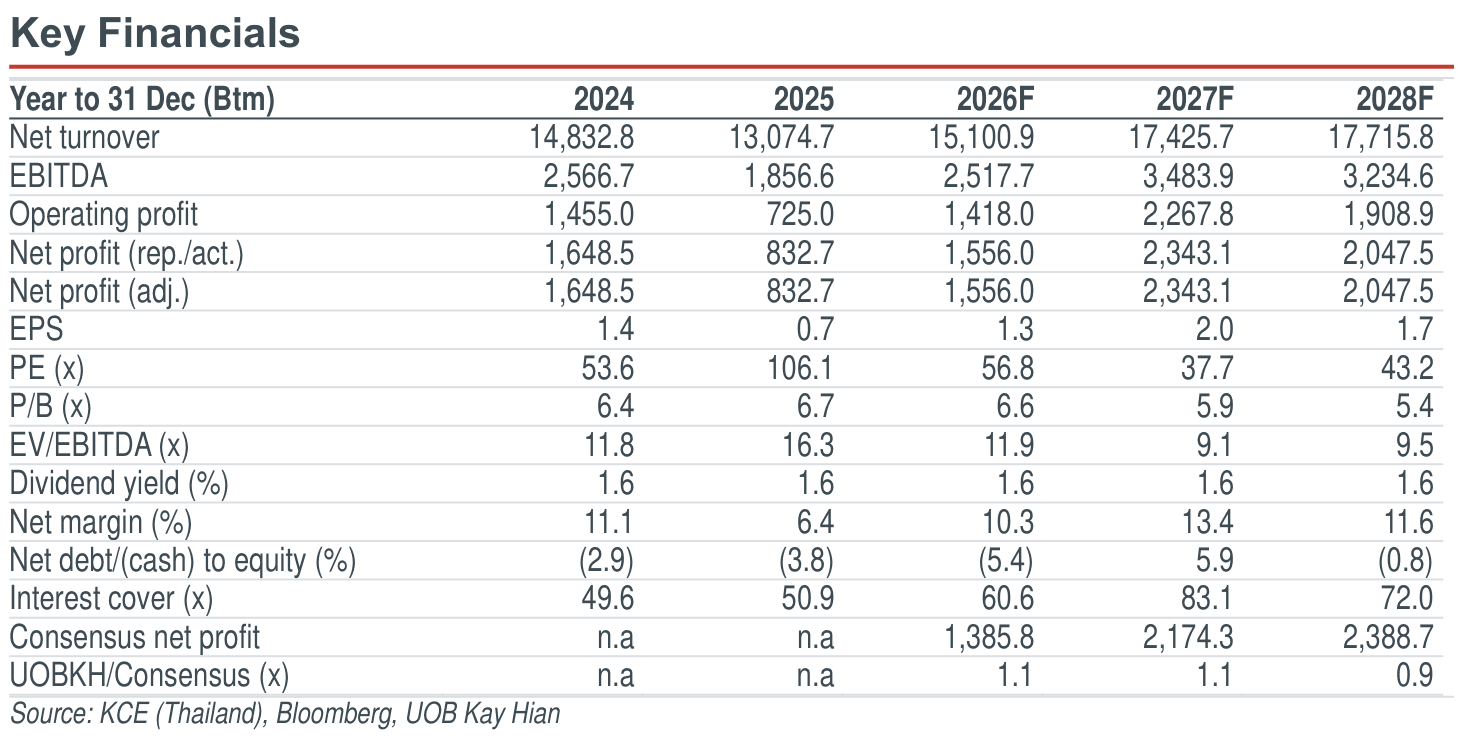
- Downgrade to HOLD with a target price of Bt80.00, as the automotive PCB earnings cycle with a 35% CAGR in 2026-28 appears largely priced in.
- Further valuation re-rating requires new earnings catalysts that could deliver incremental earnings upside on top of the existing earnings upcycle.
Analysis
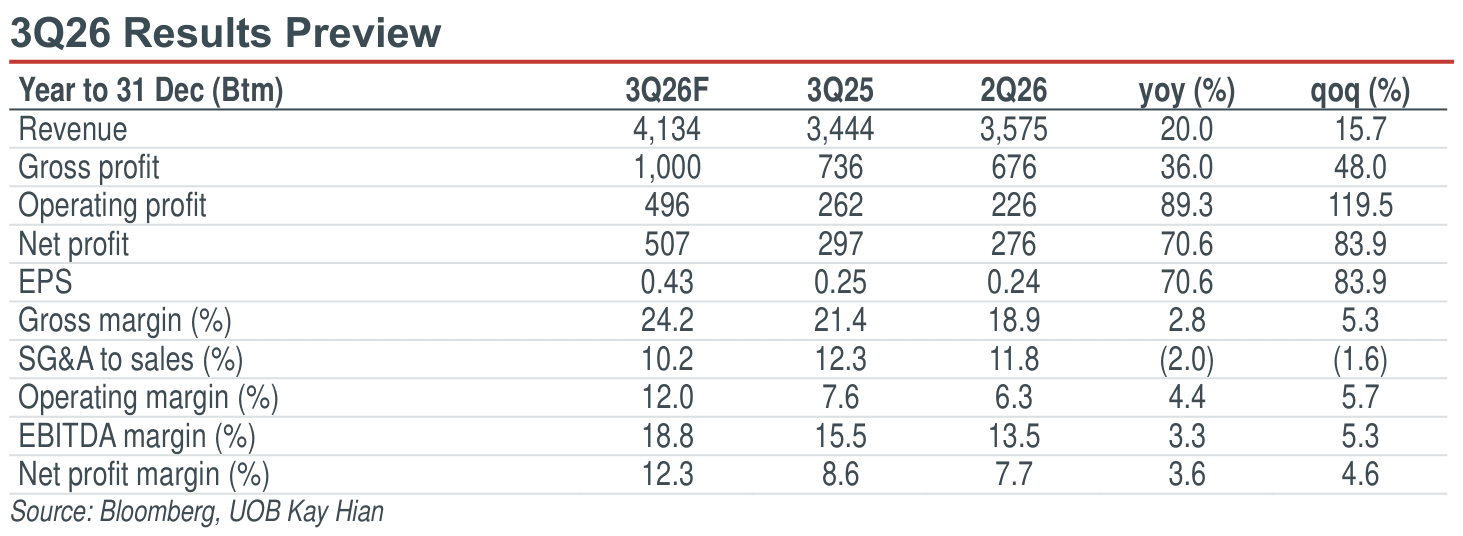
- 3Q26 earnings are expected to be strong, driven by strong sales volume and higher PCB prices. We expect 3Q26 net profit of Bt507m (+71% yoy, +84% qoq), similar to the previous outlook. Strong 3Q26 earnings should be driven mainly by strong sales growth. We estimate 3Q26 sales at Bt4.13b (+20% yoy, +16% qoq), driven by a 9% qoq increase in PCB shipment volume, based on management’s latest guidance, and a 9% increase in PCB ASPs in 3Q26 as KCE (Thailand) (KCE) will start to increase PCB prices for customers to reflect higher raw material costs, including those related to the fiberglass shortage.
- Gross margin could improve significantly in 2H26, driven by higher PCB prices, market share gains and economies of scale. We expect gross margin to significantly improve from a low base to 24.2% in 3Q26 before remaining flat in 4Q26 due to the low season (vs18.3% in 1H26, 25.0% guidance in 2H26), driven by higher PCB ASPs, market share gains and higher PCB shipment volumes, as well as economies of scale. Our 9M26 earnings account for 67% of our full-year forecast.
Highlights
- We expect KCE to post strong earnings of Bt507m (+71% yoy, +84% qoq), driven by strong sales volume and higher PCB prices.
- Humanoid robot projects offer long-term diversification potential, but are unlikely to contribute meaningfully to earnings over the next several years in our forecasts.
- Downgrade to HOLD with a target price of Bt80.00, as the automotive PCB earnings cycle with a 35% CAGR in 2026-28 appears largely priced in.
- Further valuation re-rating requires new earnings catalysts that could deliver incremental earnings upside on top of the existing earnings upcycle.
Analysis
- 3Q26 earnings are expected to be strong, driven by strong sales volume and higher PCB prices. We expect 3Q26 net profit of Bt507m (+71% yoy, +84% qoq), similar to the previous outlook. Strong 3Q26 earnings should be driven mainly by strong sales growth. We estimate 3Q26 sales at Bt4.13b (+20% yoy, +16% qoq), driven by a 9% qoq increase in PCB shipment volume, based on management’s latest guidance, and a 9% increase in PCB ASPs in 3Q26 as KCE (Thailand) (KCE) will start to increase PCB prices for customers to reflect higher raw material costs, including those related to the fiberglass shortage.
- Gross margin could improve significantly in 2H26, driven by higher PCB prices, market share gains and economies of scale. We expect gross margin to significantly improve from a low base to 24.2% in 3Q26 before remaining flat in 4Q26 due to the low season (vs18.3% in 1H26, 25.0% guidance in 2H26), driven by higher PCB ASPs, market share gains and higher PCB shipment volumes, as well as economies of scale. Our 9M26 earnings account for 67% of our full-year forecast.
HOLD (Downgraded)
Current price:
Target price:
Upside:
Previous TP :
Bt74.75
Bt80.00
7.02%
Bt65.00
Analyst
Analyst
Sirithat Prasertwuti
Sirithat@uobkh.co.thIMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


