

Company Coverage
Bangchak Corporation (BCP TB): Expect Another Solid Quarter
BUY (Maintained)
Current price:
Target price:
Upside:
Bt52.25
Bt65.00
25.6%
Analyst
Highlights
- Despite schedule maintenance of Sriracha refinery and government measures requesting diesel price discounts, we expect 3Q26 core profit to decline only 9% qoq but increase 249% yoy to Bt11.1b, driven by robustness GRM, SAF and the renewable business.
- We still expect the overall outlook to be better than pre-war levels.
- Maintain BUY with a target price of Bt65.00.
Analysis
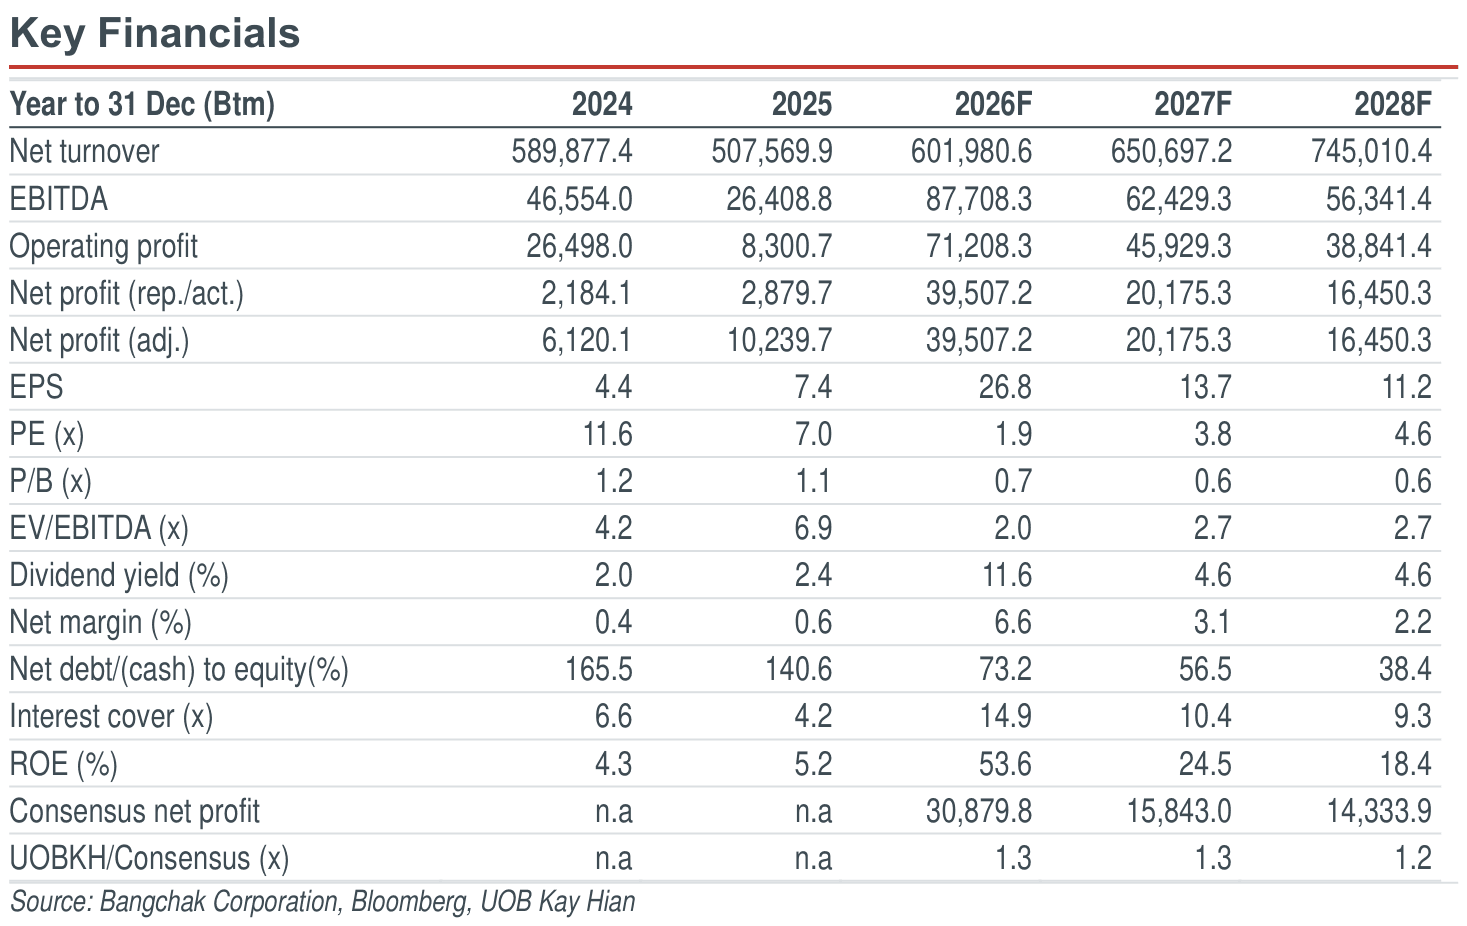
- Another strong quarter, despite a high comparison base. We forecast Bangchak Corporation (BCP) to report 3Q26 net profit of Bt10.7b (+869% yoy, -12% qoq), with core profit of Bt11.1b (+249% yoy, -9% qoq). The strong yoy improvement should be driven mainly by higher refining margins (GRM), increased contributions from the Sustainable Aviation Fuel (SAF), and the renewable business. However, earnings are likely to decline qoq due to lower refinery throughput, softer refining margins and higher hedging losses. Our forecast implies 9M26 core profit of Bt33.1b (+435% yoy), highlighting the significant improvement in BCP's profitability.
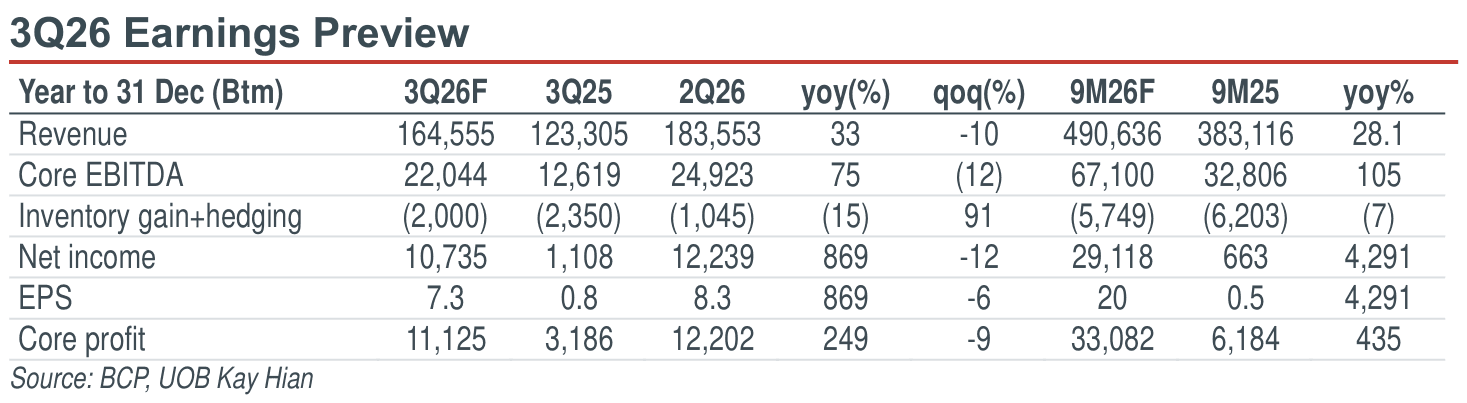
- Refining remains the key earnings driver. With resilient diesel and jet fuel cracks, we estimate refining core EBITDA, excluding inventory gains, at Bt11.6b (+121% yoy, -25% qoq), supported by a still-strong base GRM of US$17.80/bbl, compared with US$7.38/bbl in 3Q25 and US$18.41/bbl in 2Q26. Refinery run rate is expected to decline to approximately 261kbd, from 272.6kbd in 2Q26, reflecting schedule maintenance of Sriracha refinery. We also estimate inventory gains (net of hedging loss) to a total loss of Bt2.0b.
Highlights
- Despite schedule maintenance of Sriracha refinery and government measures requesting diesel price discounts, we expect 3Q26 core profit to decline only 9% qoq but increase 249% yoy to Bt11.1b, driven by robustness GRM, SAF and the renewable business.
- We still expect the overall outlook to be better than pre-war levels.
- Maintain BUY with a target price of Bt65.00.
Analysis
- Another strong quarter, despite a high comparison base. We forecast Bangchak Corporation (BCP) to report 3Q26 net profit of Bt10.7b (+869% yoy, -12% qoq), with core profit of Bt11.1b (+249% yoy, -9% qoq). The strong yoy improvement should be driven mainly by higher refining margins (GRM), increased contributions from the Sustainable Aviation Fuel (SAF), and the renewable business. However, earnings are likely to decline qoq due to lower refinery throughput, softer refining margins and higher hedging losses. Our forecast implies 9M26 core profit of Bt33.1b (+435% yoy), highlighting the significant improvement in BCP's profitability.
- Refining remains the key earnings driver. With resilient diesel and jet fuel cracks, we estimate refining core EBITDA, excluding inventory gains, at Bt11.6b (+121% yoy, -25% qoq), supported by a still-strong base GRM of US$17.80/bbl, compared with US$7.38/bbl in 3Q25 and US$18.41/bbl in 2Q26. Refinery run rate is expected to decline to approximately 261kbd, from 272.6kbd in 2Q26, reflecting schedule maintenance of Sriracha refinery. We also estimate inventory gains (net of hedging loss) to a total loss of Bt2.0b.
BUY (Maintained)
Current price:
Target price:
Upside:
Bt52.25
Bt65.00
25.6%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


