Company Coverage
Airports of Thailand (AOT TB): Expect Robust Earnings In 4QFY26, Supported By PSC
BUY (Maintained)
Current price:
Target price:
Upside:
Bt58.00
Bt85.00
+46.6%
Analyst
Analyst
Nonpawit Vathanadachakul
Highlights
- We expect AOT to report a robust 4QFY26 net profit of Bt5.6b (+45.5% yoy, +26.5% qoq), supported by the first full quarter of the new rate of PSC.
- Despite the headwinds from the flight cancellation due to flood in late-Sep 26 to early-Oct 26, the impact is insignificant and the air traffic is improving.
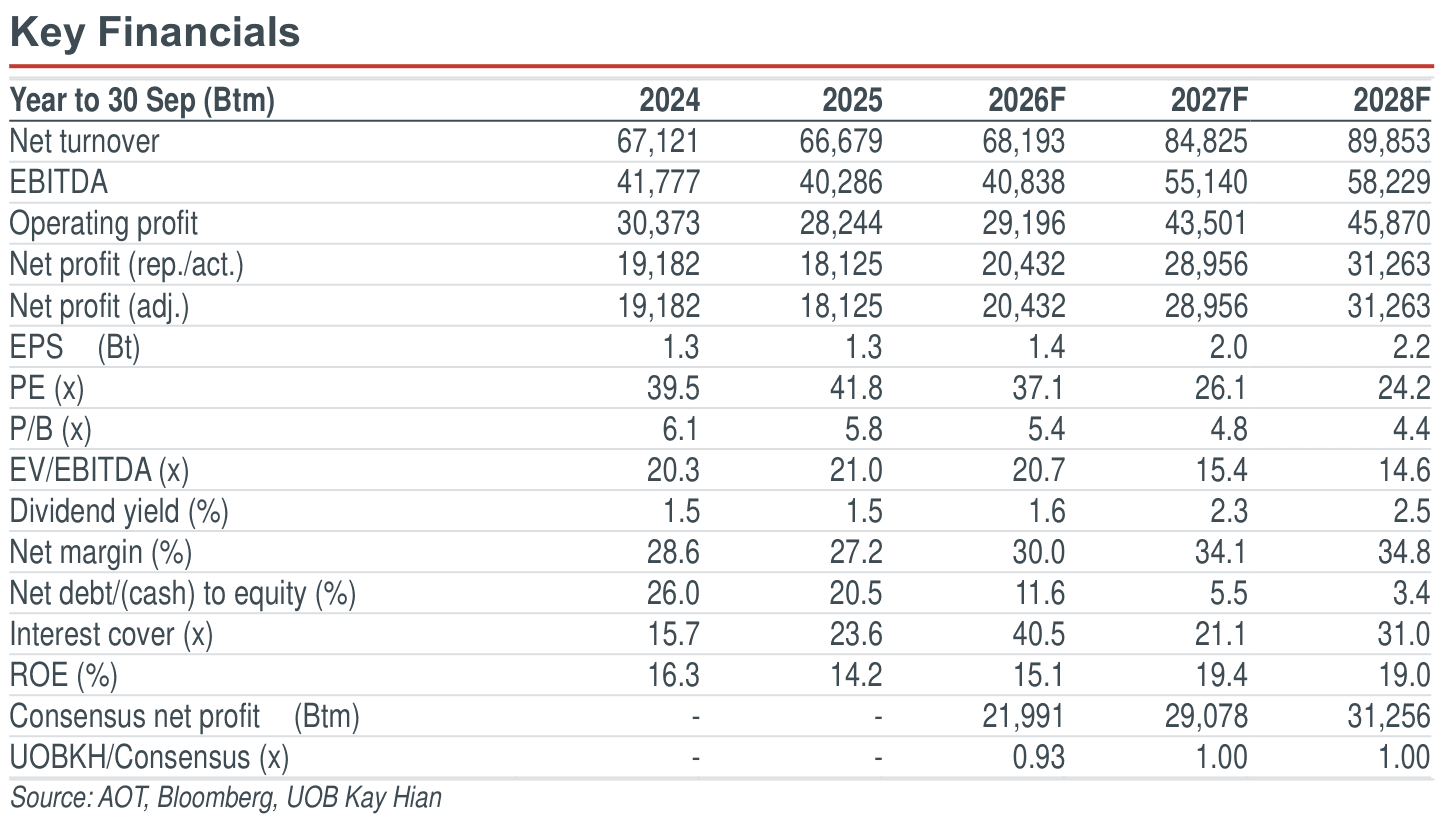
- We remain optimistic about AOT’s prospects in the high travel season which continues to be supported by the new PSC rate. AOT remains one of our top picks; maintain BUY with a target price of Bt85.00.
Analysis
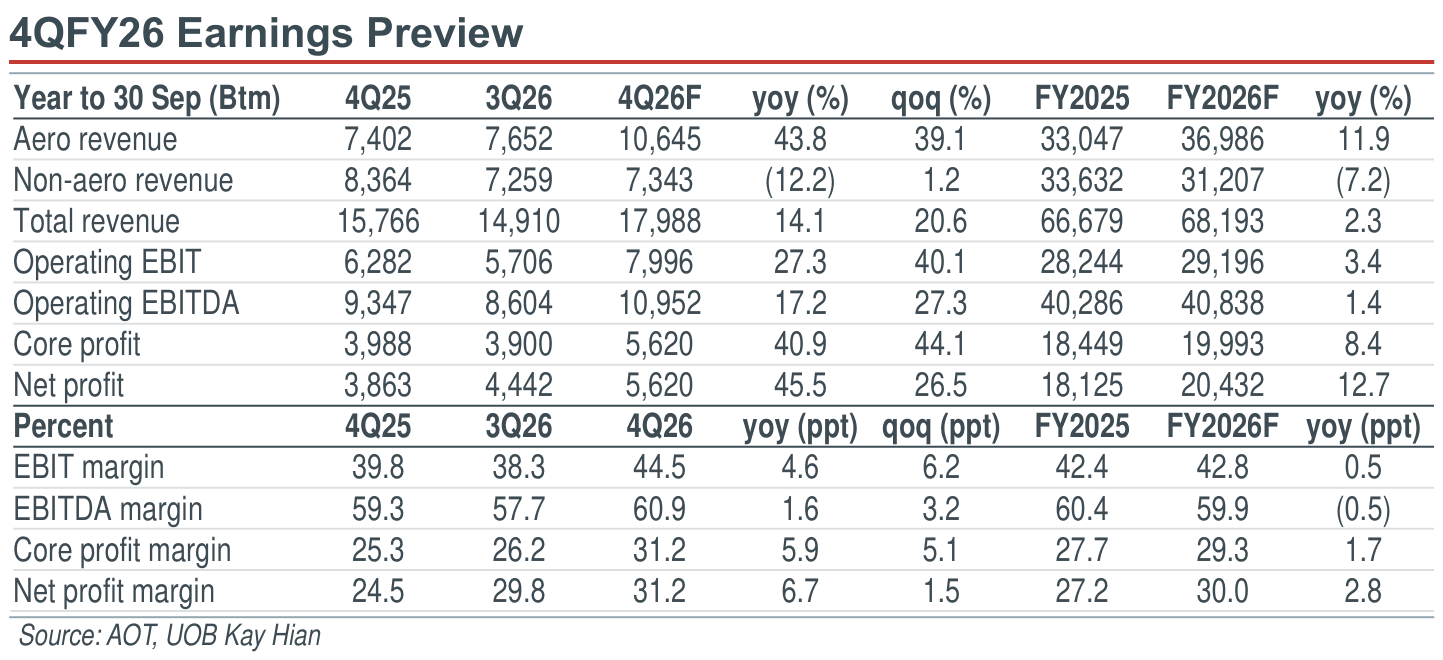
- Robust 4QFY26 earnings expected. Airports of Thailand (AOT) should report earnings of Bt5.6b (+45.5% yoy, +26.5% qoq) in 4QFY26. The strong yoy earnings growth should be driven by the first full quarter with the new Passenger Service Charge (PSC) rate at Bt1,120 per international passenger in effect. The top-line should be at Bt18.0b (+14.1% yoy, +20.6% qoq) with the 56.3% yoy and 49.1% qoq increases in PSC revenue offsetting the reduction of concession revenue from the new agreement with King Power Duty Free (KPD). Operational statistics weakened yoy in 4QFY26 due to the high airfare caused by the high fuel costs of airlines. International passenger volume dropped by 1.9% yoy, and domestic passenger volume dropped by 5.2% yoy, resulting in a 3.2% yoy decline in total passengers. Total flights also declined by 2.6% yoy. The EBITDA margins should still expand yoy and should nearly match 2QFY26, which is the strongest quarter in FY26.
Highlights
- We expect AOT to report a robust 4QFY26 net profit of Bt5.6b (+45.5% yoy, +26.5% qoq), supported by the first full quarter of the new rate of PSC.
- Despite the headwinds from the flight cancellation due to flood in late-Sep 26 to early-Oct 26, the impact is insignificant and the air traffic is improving.
- We remain optimistic about AOT’s prospects in the high travel season which continues to be supported by the new PSC rate. AOT remains one of our top picks; maintain BUY with a target price of Bt85.00.
Analysis
- Robust 4QFY26 earnings expected. Airports of Thailand (AOT) should report earnings of Bt5.6b (+45.5% yoy, +26.5% qoq) in 4QFY26. The strong yoy earnings growth should be driven by the first full quarter with the new Passenger Service Charge (PSC) rate at Bt1,120 per international passenger in effect. The top-line should be at Bt18.0b (+14.1% yoy, +20.6% qoq) with the 56.3% yoy and 49.1% qoq increases in PSC revenue offsetting the reduction of concession revenue from the new agreement with King Power Duty Free (KPD). Operational statistics weakened yoy in 4QFY26 due to the high airfare caused by the high fuel costs of airlines. International passenger volume dropped by 1.9% yoy, and domestic passenger volume dropped by 5.2% yoy, resulting in a 3.2% yoy decline in total passengers. Total flights also declined by 2.6% yoy. The EBITDA margins should still expand yoy and should nearly match 2QFY26, which is the strongest quarter in FY26.
BUY (Maintained)
Current price:
Target price:
Upside:
Bt58.00
Bt85.00
+46.6%
Analyst
Analyst
Nonpawit Vathanadachakul
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


