Company Coverage
Aeon Thana Sinsap (Thailand) (AEONTS TB) - 2QFY27: Results Miss; Credit Costs And NPL Ratio Jump QOQ
HOLD (Downgraded)
Current price:
Target price:
Upside:
Previous TP :
Bt90.25
Bt98.00
+8.6%
Bt120.00
Analyst
Highlights
- AEONTS posted a 2QFY27 net profit of Bt642m, down 19% yoy and 19% qoq.
- The higher provisioning reflected the deterioration in asset quality for the HP loan portfolio.
- Downgrade to HOLD with a lower target price of Bt98.00 (previously: Bt120.00).
Analysis
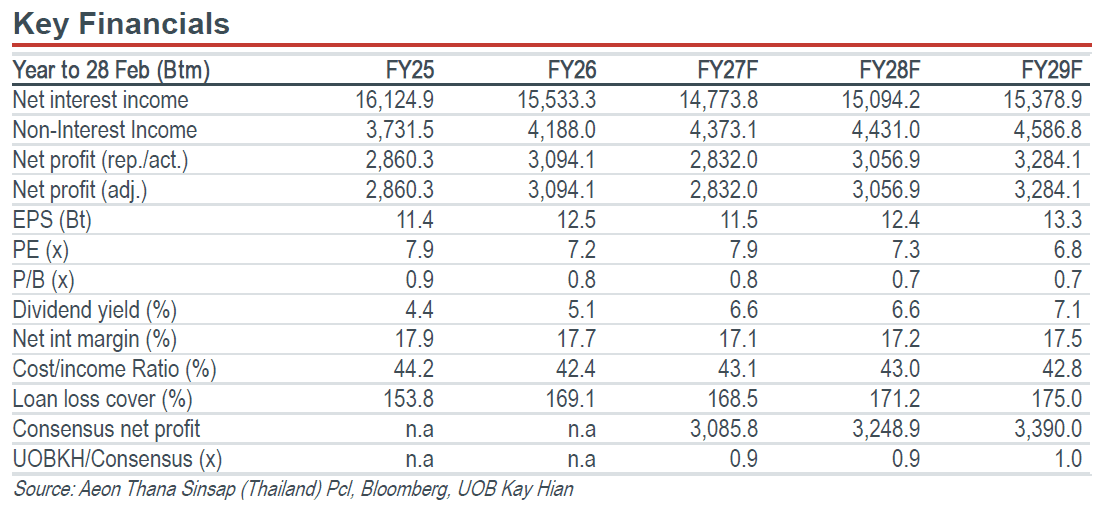
- 2QFY27 results miss. Aeon Thana Sinsap (Thailand) (AEONTS) posted a 2QFY277 net profit of Bt642m, down 19% yoy and 19% qoq, missing our and consensus expectations by 8% and 18%, respectively. Although there was a gain from sales of written-off receivables in this quarter, the higher provisioning dragged the bottom line. Several key items were in line with our forecasts except for the net interest income that came under our estimates by 7%. Excluding provisioning, the company’s pre-provision operating profit declined by 4% yoy but increased by 6% qoq.
- A gain from sale of written-off receivables to help increase non-II. In 2QFY27, AEONTS reported a gain from the sale of written-off receivables of Bt144m, which is in line with our expectations of not exceeding Bt150m. Hence, non-interest income rose by 8% yoy and 12% qoq to Bt1.1b in 2QFY27.
- Loan portfolio contracted yoy and qoq in 2QFY27. AEONTS reported loans outstanding of Bt84.4b in 2QFY27, down 4% yoy and 1% qoq. Gross loans in the credit card portfolio declined 1.2% qoq in 2QFY27, while gross loans in the personal loan portfolio dropped 0.6% qoq. Meanwhile, the hire-purchase (HP) portfolio shrank 3.6% qoq during the period. The shrinking in the HP portfolio was in line with the previous guidance that the company has freezed the loan portfolio for a while after a deterioration in asset quality.
- Credit costs jumped qoq. NPL ratio jumped qoq from 5.6% in 1QFY27 to 5.9% in 2QFY27, which mainly came from the deterioration in asset quality from the HP portfolio according to the guidance. Meanwhile, AEONTS reported a 26% qoq increase to Bt2b in provision expenses in 2QFY27. The higher provisioning qoq reflected the asset quality adjustment in the domestic HP business and the loan portfolio in Cambodia. As a result, credit costs jumped 203bp qoq to 948bp in 2QFY27. According to the company’s guidance, it is expected to take few quarters for the asset quality issue in the HP portfolio to be resolved. Therefore, we cut our forecasts to reflect the deterioration in asset quality and the higher credit cost outlook.
Highlights
- AEONTS posted a 2QFY27 net profit of Bt642m, down 19% yoy and 19% qoq.
- The higher provisioning reflected the deterioration in asset quality for the HP loan portfolio.
- Downgrade to HOLD with a lower target price of Bt98.00 (previously: Bt120.00).
Analysis
- 2QFY27 results miss. Aeon Thana Sinsap (Thailand) (AEONTS) posted a 2QFY277 net profit of Bt642m, down 19% yoy and 19% qoq, missing our and consensus expectations by 8% and 18%, respectively. Although there was a gain from sales of written-off receivables in this quarter, the higher provisioning dragged the bottom line. Several key items were in line with our forecasts except for the net interest income that came under our estimates by 7%. Excluding provisioning, the company’s pre-provision operating profit declined by 4% yoy but increased by 6% qoq.
- A gain from sale of written-off receivables to help increase non-II. In 2QFY27, AEONTS reported a gain from the sale of written-off receivables of Bt144m, which is in line with our expectations of not exceeding Bt150m. Hence, non-interest income rose by 8% yoy and 12% qoq to Bt1.1b in 2QFY27.
- Loan portfolio contracted yoy and qoq in 2QFY27. AEONTS reported loans outstanding of Bt84.4b in 2QFY27, down 4% yoy and 1% qoq. Gross loans in the credit card portfolio declined 1.2% qoq in 2QFY27, while gross loans in the personal loan portfolio dropped 0.6% qoq. Meanwhile, the hire-purchase (HP) portfolio shrank 3.6% qoq during the period. The shrinking in the HP portfolio was in line with the previous guidance that the company has freezed the loan portfolio for a while after a deterioration in asset quality.
- Credit costs jumped qoq. NPL ratio jumped qoq from 5.6% in 1QFY27 to 5.9% in 2QFY27, which mainly came from the deterioration in asset quality from the HP portfolio according to the guidance. Meanwhile, AEONTS reported a 26% qoq increase to Bt2b in provision expenses in 2QFY27. The higher provisioning qoq reflected the asset quality adjustment in the domestic HP business and the loan portfolio in Cambodia. As a result, credit costs jumped 203bp qoq to 948bp in 2QFY27. According to the company’s guidance, it is expected to take few quarters for the asset quality issue in the HP portfolio to be resolved. Therefore, we cut our forecasts to reflect the deterioration in asset quality and the higher credit cost outlook.
HOLD (Downgraded)
Current price:
Target price:
Upside:
Previous TP :
Bt90.25
Bt98.00
+8.6%
Bt120.00
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


