

Wealth Daily
AI Investment Expands as Boeing Sinks Before Fed Decision
Today’s Must-Know News
Overnight Markets
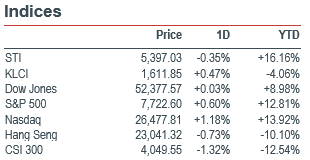
Market Movers: At the 27 October close, the S&P 500 gained 0.60%. Meta Platforms (META US) fell 1.64% after pricing US$37.5bn of common and convertible-preferred offerings, increasing financing capacity but adding dilution. NVIDIA and AMD separately committed US$3bn and US$1bn to the offering. NVIDIA (NVDA US) rose 0.90% as Vera Rubin systems and Vera CPUs became generally available on Oracle Cloud Infrastructure, with multigigawatt expansion planned. Availability broadens potential adoption, although the expansion is not a disclosed firm sales order. Boeing (BA US) dropped 10.69% after a US$0.34 core quarterly loss per share and a US$697m commercial-airplane operating loss. Revenue rose about 4% YoY, but recovering production has yet to translate into consistent profitability. The contrasting developments highlight both AI investment demand and the importance of converting capacity into cash. (Meta / NVIDIA / Meta plan / NVIDIA / AMD / Boeing / Reuters / eOption) Meta Platforms (META US) and NVIDIA (NVDA US) are our Core Recommendations.
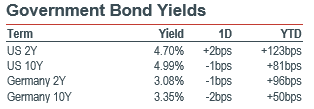
Macro: The forthcoming Fed decision is due at 02:00 SGT on 29 October, followed by the press conference at 02:30 A hold at 3.75–4.00% is expected. Guidance on further tightening remains the key issue: persistent inflation could keep policy restrictive, while an overly dovish message risks undermining confidence in inflation control. (Federal Reserve / Reuters)
AI
• NVIDIA and Oracle expand commercial access to Rubin infrastructure. NVIDIA (NVDA US) made Vera Rubin NVL72 systems and Vera CPUs available on Oracle Cloud Infrastructure, with plans for multigigawatt superclusters. Each rack connects 72 GPUs, while independent CPU and GPU scaling aims to reduce idle capacity. Shares rose 0.90% to US$217.94. Broader availability expands potential commercial adoption, although no order value or deployment timetable has been disclosed. (NVIDIA / Market data) NVIDIA (NVDA US) is our Core Recommendation.
• Meta prices US$37.5bn in equity offerings, with US$3bn committed by NVIDIA. Meta Platforms (META US) priced US$25bn of common shares at US$625 and US$12.5bn of convertible preferred securities. NVIDIA committed US$3bn to the offering alongside deeper Muse collaboration. Shares fell 1.64% to US$620.19. The financing strengthens investment capacity but adds dilution risk and a 6.50% preferred dividend. The US$37.5bn in priced offerings remains separate from the uncommitted US$60bn at-the-market programme. (Meta / NVIDIA / Meta plan / Market data) Meta Platforms (META US) is our Core Recommendation.
• Advanced Micro Devices deepens its infrastructure partnership with Meta. Advanced Micro Devices (AMD US) has installed initial Helios systems at Meta, where they are being tested; EPYC processors support Muse, and Instinct GPUs already serve training workloads. AMD committed US$1bn to Meta’s equity offering, and shares rose 5.45% to US$560.26. The relationship expands AMD’s infrastructure reach, but broader Helios deployment remains prospective and no incremental sales value was disclosed. (AMD / Market data)
• Celestica surges on ambitious 2027 revenue guidance. Celestica (CLS US) shares rose 12.12% to US$276.54 after the prior evening’s results forecast 2027 revenue of US$40bn, up about 90%. Q3 revenue grew 83% YoY to US$5.83bn, and adjusted EPS increased 109% to US$3.30. AI demand supports expansion, but 2026 free-cash-flow guidance fell to US$460m from US$600m as working-capital requirements rose. (Celestica / Market data)
Americas
• The Boeing Company’s aircraft losses unsettle investors. The Boeing Company (BA US) shares fell 10.69% to US$168.18 after Q3 commercial-airplane losses reached US$697m, a negative 6.5% margin. Group revenue rose 4% YoY to US$24.19bn, but core loss per share of US$0.34 exceeded the US$0.20 loss expected. Commercial deliveries edged up to 161 from 160; profitable production, rather than backlog growth alone, remains the key recovery test. (Boeing / Reuters / eOption / Market data)
• Visa sustains payments growth. Visa (V US) reported fiscal Q4 revenue growth of 13% YoY to US$12.1bn and an increase in adjusted EPS of 17% to US$3.48. Payments volume grew 9%, cross-border volume excluding intra-Europe expanded 14%, and processed transactions rose 10%. Growth supports transaction-led earnings, although client incentives increased faster at 21%. Results followed the regular close, so the earlier share-price move is not an earnings reaction. (Visa / Publicnow)
• The Coca-Cola Company raises guidance on volume growth. The Coca-Cola Company (KO US) reported Q3 revenue growth of 7% YoY to US$13.4bn and an 11% rise in comparable EPS to US$0.91. Unit-case volume increased 5%, supporting organic-sales growth beyond pricing. Management now expects at least 5% annual organic revenue growth, 11% comparable EPS growth and US$13bn in free cash flow. Shares fell 1.64% to US$91.18; sustained volume execution remains crucial. (Coca-Cola / Market data) The Coca-Cola Company (KO US) is our Investment Opportunity.
• Cadence Design Systems rallies on design demand. Cadence Design Systems (CDNS US) rose 6.49% to US$343.08 in the first session after results. Q3 revenue grew 22% YoY to US$1.63bn, and adjusted EPS reached US$2.11 versus US$1.93. Annual adjusted EPS guidance is US$8.37–8.43. AI hardware complexity supports design demand, but adjusted operating margin fell to 44.1% from 47.6%, highlighting profit-conversion risk. (Cadence / Market data)
• Corning Incorporated monetises AI optical demand. Corning Incorporated (GLW US) reported Q3 core revenue growth of 19% YoY to US$5.08bn and a 36% rise in core EPS to US$0.91. Optical sales expanded 44% to US$2.38bn as generative-AI products more than doubled. Core operating margin widened 310 basis points to 22.7%. Shares fell 1.13% to US$126.30; capacity delivery and cash generation remain essential as Corning expands to meet demand. (Corning / Market data)
• Constellation Energy Corporation secures conditional financing of up to US$5bn. Constellation Energy Corporation (CEG US) would benefit from the conditional DOE loan commitment, which would support uprates at existing plants, reducing financing costs. 20-year Google and Amazon agreements supported more than US$7bn of investment and approximately 1,080MW of added capacity. Existing-site expansion addresses rising power demand, but the financing remains subject to due diligence and definitive documentation, with no funds yet received. (Constellation)
• United Parcel Service upgrades revenue and cash-flow forecasts. United Parcel Service (UPS US) shares rose 5.75% to US$106.09 as Q3 revenue grew 6.7% YoY to US$22.9bn. Adjusted EPS was US$1.69 versus US$1.74; the prior year included a US$0.30 sale-leaseback gain. Annual revenue guidance increased to US$92.6bn from US$91.2bn and free cash flow to US$6.1bn from US$5.5bn. The upgrade supports recovery, with package mix and efficiency still critical. (UPS / Reuters / Market data)
• Pfizer’s Elrexfio clears an efficacy hurdle. Pfizer (PFE US) reported that the 523-patient Phase 3 MagnetisMM-32 trial met its progression-free-survival endpoint in previously treated multiple myeloma, with estimated 18-month progression-free survival of 68%. Pfizer plans regulatory submissions, supporting potential earlier-line use. Overall-survival data remain immature, while grade-three-or-higher infections occurred in 27.5% of Elrexfio patients versus 18.1% of controls; benefit-risk assessment matters before assuming broader adoption. (Pfizer)
• HCA Healthcare faces uninsured-care pressure. HCA Healthcare (HCA US) reported Q3 revenue growth of 3.6% YoY to US$19.85bn and an increase in adjusted EPS of 3.7% to US$7.22. Same-facility admissions grew 2.7%, but increased uninsured care caused an estimated US$400m pretax headwind. Shares fell 3.29% to US$449.96 despite management expecting results in the upper half of annual guidance. Patient volumes support growth, while payer mix remains a profitability risk. (HCA / Market data)
• Constellation Energy Corporation secures conditional financing of up to US$5bn. Constellation Energy Corporation (CEG US) would benefit from the conditional DOE loan commitment, which would support uprates at existing plants, reducing financing costs. 20-year Google and Amazon agreements supported more than US$7bn of investment and approximately 1,080MW of added capacity. Existing-site expansion addresses rising power demand, but the financing remains subject to due diligence and definitive documentation, with no funds yet received. (Constellation)
• United Parcel Service upgrades revenue and cash-flow forecasts. United Parcel Service (UPS US) shares rose 5.75% to US$106.09 as Q3 revenue grew 6.7% YoY to US$22.9bn. Adjusted EPS was US$1.69 versus US$1.74; the prior year included a US$0.30 sale-leaseback gain. Annual revenue guidance increased to US$92.6bn from US$91.2bn and free cash flow to US$6.1bn from US$5.5bn. The upgrade supports recovery, with package mix and efficiency still critical. (UPS / Reuters / Market data)
• Royal Caribbean Group raises earnings guidance. Royal Caribbean Group (RCL US) shares rose 5.46% to US$295.92 after Q3 revenue grew about 9% YoY to US$5.59bn and adjusted EPS reached US$6.57 versus US$5.75. Annual adjusted EPS guidance increased to US$17.85–17.95, with 2027 bookings ahead at higher prices. Demand supports the outlook, but expenses deferred into Q4 mean the earnings beat is not entirely a lasting efficiency gain. (Royal Caribbean / Reuters / Market data)
• Pfizer’s Elrexfio clears an efficacy hurdle. Pfizer (PFE US) reported that the 523-patient Phase 3 MagnetisMM-32 trial met its progression-free-survival endpoint in previously treated multiple myeloma, with estimated 18-month progression-free survival of 68%. Pfizer plans regulatory submissions, supporting potential earlier-line use. Overall-survival data remain immature, while grade-three-or-higher infections occurred in 27.5% of Elrexfio patients versus 18.1% of controls; benefit-risk assessment matters before assuming broader adoption. (Pfizer)
• HCA Healthcare faces uninsured-care pressure. HCA Healthcare (HCA US) reported Q3 revenue growth of 3.6% YoY to US$19.85bn and an increase in adjusted EPS of 3.7% to US$7.22. Same-facility admissions grew 2.7%, but increased uninsured care caused an estimated US$400m pretax headwind. Shares fell 3.29% to US$449.96 despite management expecting results in the upper half of annual guidance. Patient volumes support growth, while payer mix remains a profitability risk. (HCA / Market data)
Greater China
• HSBC profit rises, but revenue disappointment weighs on shares. HSBC (0005.HK) reported third-quarter pre-tax profit of US$9.6bn, up 32% YoY, and a buyback of up to US$1bn. Revenue of US$18.6bn missed expectations as wealth growth slowed, Reuters reported. Hong Kong shares fell 5.56% to HK$134.30. Absent prior-year legal provisions of US$1.4bn boosted profit, making recurring revenue momentum the more useful test. (Company / Reuters / Market data) HSBC (0005.HK) is our Core Recommendation.
• Hengrui earnings growth benefits from licensing income. Hengrui Pharma (1276.HK) reported third-quarter revenue of RMB8.95bn, up 20.6% YoY, and attributable profit of RMB2.46bn, up 88.9%, after the market closed. Nine-month innovative-drug sales grew 17.1% to RMB13.87bn, while licensing revenue rose 31.1% to RMB2.78bn. Product growth supports commercial progress, although uneven licensing payments can make quarterly earnings less representative of recurring momentum. (Company / Reuters)
• Meituan secures tighter terms for offshore yuan funding. Meituan (3690.HK) launched RMB8bn of offshore yuan bonds after orders exceeded RMB20bn, Reuters reported. Its five-year tranche yielded 2.50% versus initial guidance of 2.90%, while ten-year pricing tightened to 3.10% from 3.60%. Proceeds will refinance offshore debt. The final terms improve funding flexibility, although strong bond demand does not establish an operating-margin recovery. (Reuters) Meituan (3690.HK) is our Investment Opportunity.
• China profit recovery remains uneven across industries. China’s industrial profits rose 14.4% YoY in September, accelerating from August’s 4.2%. Nine-month profits increased 15.5% to RMB6.03tn. Electronics and communications-equipment profits more than doubled over nine months, while automotive profits fell 22.8%. Official figures show a divergent recovery: aggregate profitability provides limited reassurance for consumer-facing manufacturers facing weak demand and intense competition. (NBS / Reuters)
Asia ex. China
• Korea’s growth accelerates, led by exports and investment. South Korea’s third-quarter GDP expanded 1.0% quarter on quarter, versus 0.6% previously and a 0.7% Reuters poll forecast; growth was 3.4% YoY. Exports rose 2.3% sequentially and facilities investment increased 4.1%, while private consumption fell 0.2%. The Bank of Korea’s estimate shows an export-led recovery, leaving momentum dependent on semiconductor demand rather than consumption. (Bank of Korea / Reuters)
• Canon’s medical supply constraints outweigh stronger quarterly profit. Canon (7751.T) increased third-quarter sales 4.9% YoY to JPY1.159tn and operating profit 10.3% to JPY97.1bn, but cut full-year operating-profit guidance to JPY456bn from JPY465bn. The estimated medical-business sales impact from production constraints doubled to JPY90bn. AI-related component shortages delayed normalisation until next year, illustrating how chip-sector demand can constrain growth for equipment makers. (Company / Investing.com)•
• ST Engineering’s contract wins broaden revenue visibility. ST Engineering (S63.SI) secured S$5.6bn of third-quarter contracts, taking nine-month awards to S$13.2bn. The total excludes a S$1.7bn New Jersey Turnpike contract already included in its order book. The wins span three business segments. Future workloads improve, but the company expects no material current-year earnings impact, making execution and cash conversion the key tests. (Company / The Business Times)
EMEA and Others
• GNovartis lifts its outlook despite pipeline impairments. Novartis (NOVN.SW) raised its full-year core operating-profit outlook to flat to low-single-digit growth in constant currencies from a low-single-digit decline. Third-quarter sales rose 4% YoY to US$14.52bn and core operating profit increased 11% in reported dollars to US$6.04bn. However, US$2.2bn of impairments pushed reported operating profit down 59%, contrasting medicines’ resilience with pipeline investment risk. (Company / Reuters)
• Besi rallies as Applied Materials strengthens its strategic stake. BE Semiconductor Industries (BESI.AS) rose 11.41% to EUR163.05 after acknowledging Applied Materials’ plan for an approximately 20% holding. Their hybrid-bonding partnership supports advanced chip packaging for AI. Applied described the investment as long term and intends no board representation. The reaction signals confidence in the partnership, while execution remains a key investment test. (Company / Market data / Investing.com)
• Mercedes cuts its outlook as China and costs weigh. Mercedes-Benz (MBG.DE) cut its full-year adjusted cars return-on-sales forecast to 2–3% from 3–5%, citing China weakness and material costs. Preliminary third-quarter EBIT of EUR1.77bn beat the company’s EUR1.6bn consensus, but industrial free cash flow of EUR172m missed EUR422m expectations. Weak cash generation makes the outlook cut more consequential than the profit surprise. (Company / dpa via Bernama)
• Reckitt trims growth expectations as volumes remain subdued. Reckitt (RKT.L) lowered full-year core like-for-like revenue growth guidance to 3.5–4.5% from 4–5%. Third-quarter core revenue was GBP2.69bn, up 3.3%, comprising 0.1% volume growth and 3.2% price and mix. North America fell 1.3% as Lysol supply constraints weighed. Limited volume momentum means restoring production and demand matters more than relying on further price increases. (Company / Reuters)
• ASSA ABLOY expands margins despite uneven construction demand. ASSA ABLOY (ASSA-B.ST) reported third-quarter sales of SEK40.77bn, up 6.9% YoY, with organic growth of 4%. Adjusted operating profit increased 11.0% to SEK7.10bn, beating Reuters’ SEK6.94bn consensus, and its margin rose to 17.4% from 16.8%. Americas and EMEIA growth contrasted with an Asian decline; pricing and efficiency support profitability through an uneven construction cycle. (Company / Reuters)
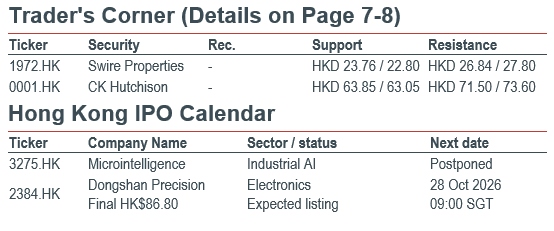
Traders' Corner
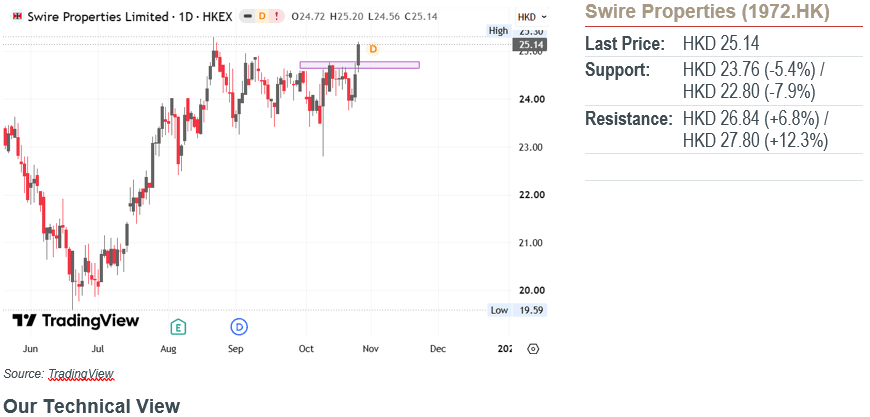
Our Technical View
Price further penetrated above its prior peak resistance zone.
The RSI is firmly established in bullish territory and continues to slope upward with strong positive velocity.
This momentum expansion confirms robust underlying trend strength as price approaches its paramount structural pivot at the HK$25.86 all-time high resistance boundary.
A decisive daily close above HK$25.86 will trigger blue-sky price discovery toward higher Fibonacci projection targets.
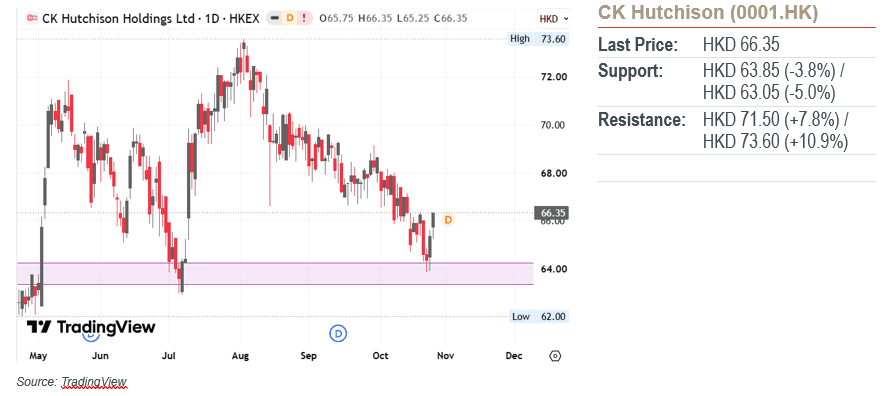
Our Technical View
Price rebounded off its prior swing-low support zone.
The RSI is rising steadily with positive velocity toward its neutral 50-midline, signaling a progressive recovery in underlying buying power.
As long as price maintains above this defended support floor, we see continued upward expansion toward overhead resistance targets.
Market Movers: At the 27 October close, the S&P 500 gained 0.60%. Meta Platforms (META US) fell 1.64% after pricing US$37.5bn of common and convertible-preferred offerings, increasing financing capacity but adding dilution. NVIDIA and AMD separately committed US$3bn and US$1bn to the offering. NVIDIA (NVDA US) rose 0.90% as Vera Rubin systems and Vera CPUs became generally available on Oracle Cloud Infrastructure, with multigigawatt expansion planned. Availability broadens potential adoption, although the expansion is not a disclosed firm sales order. Boeing (BA US) dropped 10.69% after a US$0.34 core quarterly loss per share and a US$697m commercial-airplane operating loss. Revenue rose about 4% YoY, but recovering production has yet to translate into consistent profitability. The contrasting developments highlight both AI investment demand and the importance of converting capacity into cash. (Meta / NVIDIA / Meta plan / NVIDIA / AMD / Boeing / Reuters / eOption) Meta Platforms (META US) and NVIDIA (NVDA US) are our Core Recommendations.
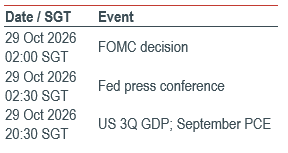
Macro: The forthcoming Fed decision is due at 02:00 SGT on 29 October, followed by the press conference at 02:30 A hold at 3.75–4.00% is expected. Guidance on further tightening remains the key issue: persistent inflation could keep policy restrictive, while an overly dovish message risks undermining confidence in inflation control. (Federal Reserve / Reuters)
AI
• NVIDIA and Oracle expand commercial access to Rubin infrastructure. NVIDIA (NVDA US) made Vera Rubin NVL72 systems and Vera CPUs available on Oracle Cloud Infrastructure, with plans for multigigawatt superclusters. Each rack connects 72 GPUs, while independent CPU and GPU scaling aims to reduce idle capacity. Shares rose 0.90% to US$217.94. Broader availability expands potential commercial adoption, although no order value or deployment timetable has been disclosed. (NVIDIA / Market data) NVIDIA (NVDA US) is our Core Recommendation.
• Meta prices US$37.5bn in equity offerings, with US$3bn committed by NVIDIA. Meta Platforms (META US) priced US$25bn of common shares at US$625 and US$12.5bn of convertible preferred securities. NVIDIA committed US$3bn to the offering alongside deeper Muse collaboration. Shares fell 1.64% to US$620.19. The financing strengthens investment capacity but adds dilution risk and a 6.50% preferred dividend. The US$37.5bn in priced offerings remains separate from the uncommitted US$60bn at-the-market programme. (Meta / NVIDIA / Meta plan / Market data) Meta Platforms (META US) is our Core Recommendation.
• Advanced Micro Devices deepens its infrastructure partnership with Meta. Advanced Micro Devices (AMD US) has installed initial Helios systems at Meta, where they are being tested; EPYC processors support Muse, and Instinct GPUs already serve training workloads. AMD committed US$1bn to Meta’s equity offering, and shares rose 5.45% to US$560.26. The relationship expands AMD’s infrastructure reach, but broader Helios deployment remains prospective and no incremental sales value was disclosed. (AMD / Market data)
• Celestica surges on ambitious 2027 revenue guidance. Celestica (CLS US) shares rose 12.12% to US$276.54 after the prior evening’s results forecast 2027 revenue of US$40bn, up about 90%. Q3 revenue grew 83% YoY to US$5.83bn, and adjusted EPS increased 109% to US$3.30. AI demand supports expansion, but 2026 free-cash-flow guidance fell to US$460m from US$600m as working-capital requirements rose. (Celestica / Market data)
Americas
• The Boeing Company’s aircraft losses unsettle investors. The Boeing Company (BA US) shares fell 10.69% to US$168.18 after Q3 commercial-airplane losses reached US$697m, a negative 6.5% margin. Group revenue rose 4% YoY to US$24.19bn, but core loss per share of US$0.34 exceeded the US$0.20 loss expected. Commercial deliveries edged up to 161 from 160; profitable production, rather than backlog growth alone, remains the key recovery test. (Boeing / Reuters / eOption / Market data)
• Visa sustains payments growth. Visa (V US) reported fiscal Q4 revenue growth of 13% YoY to US$12.1bn and an increase in adjusted EPS of 17% to US$3.48. Payments volume grew 9%, cross-border volume excluding intra-Europe expanded 14%, and processed transactions rose 10%. Growth supports transaction-led earnings, although client incentives increased faster at 21%. Results followed the regular close, so the earlier share-price move is not an earnings reaction. (Visa / Publicnow)
• The Coca-Cola Company raises guidance on volume growth. The Coca-Cola Company (KO US) reported Q3 revenue growth of 7% YoY to US$13.4bn and an 11% rise in comparable EPS to US$0.91. Unit-case volume increased 5%, supporting organic-sales growth beyond pricing. Management now expects at least 5% annual organic revenue growth, 11% comparable EPS growth and US$13bn in free cash flow. Shares fell 1.64% to US$91.18; sustained volume execution remains crucial. (Coca-Cola / Market data) The Coca-Cola Company (KO US) is our Investment Opportunity.
• Cadence Design Systems rallies on design demand. Cadence Design Systems (CDNS US) rose 6.49% to US$343.08 in the first session after results. Q3 revenue grew 22% YoY to US$1.63bn, and adjusted EPS reached US$2.11 versus US$1.93. Annual adjusted EPS guidance is US$8.37–8.43. AI hardware complexity supports design demand, but adjusted operating margin fell to 44.1% from 47.6%, highlighting profit-conversion risk. (Cadence / Market data)
• Corning Incorporated monetises AI optical demand. Corning Incorporated (GLW US) reported Q3 core revenue growth of 19% YoY to US$5.08bn and a 36% rise in core EPS to US$0.91. Optical sales expanded 44% to US$2.38bn as generative-AI products more than doubled. Core operating margin widened 310 basis points to 22.7%. Shares fell 1.13% to US$126.30; capacity delivery and cash generation remain essential as Corning expands to meet demand. (Corning / Market data)
• Constellation Energy Corporation secures conditional financing of up to US$5bn. Constellation Energy Corporation (CEG US) would benefit from the conditional DOE loan commitment, which would support uprates at existing plants, reducing financing costs. 20-year Google and Amazon agreements supported more than US$7bn of investment and approximately 1,080MW of added capacity. Existing-site expansion addresses rising power demand, but the financing remains subject to due diligence and definitive documentation, with no funds yet received. (Constellation)
• United Parcel Service upgrades revenue and cash-flow forecasts. United Parcel Service (UPS US) shares rose 5.75% to US$106.09 as Q3 revenue grew 6.7% YoY to US$22.9bn. Adjusted EPS was US$1.69 versus US$1.74; the prior year included a US$0.30 sale-leaseback gain. Annual revenue guidance increased to US$92.6bn from US$91.2bn and free cash flow to US$6.1bn from US$5.5bn. The upgrade supports recovery, with package mix and efficiency still critical. (UPS / Reuters / Market data)
• Pfizer’s Elrexfio clears an efficacy hurdle. Pfizer (PFE US) reported that the 523-patient Phase 3 MagnetisMM-32 trial met its progression-free-survival endpoint in previously treated multiple myeloma, with estimated 18-month progression-free survival of 68%. Pfizer plans regulatory submissions, supporting potential earlier-line use. Overall-survival data remain immature, while grade-three-or-higher infections occurred in 27.5% of Elrexfio patients versus 18.1% of controls; benefit-risk assessment matters before assuming broader adoption. (Pfizer)
• HCA Healthcare faces uninsured-care pressure. HCA Healthcare (HCA US) reported Q3 revenue growth of 3.6% YoY to US$19.85bn and an increase in adjusted EPS of 3.7% to US$7.22. Same-facility admissions grew 2.7%, but increased uninsured care caused an estimated US$400m pretax headwind. Shares fell 3.29% to US$449.96 despite management expecting results in the upper half of annual guidance. Patient volumes support growth, while payer mix remains a profitability risk. (HCA / Market data)
• Constellation Energy Corporation secures conditional financing of up to US$5bn. Constellation Energy Corporation (CEG US) would benefit from the conditional DOE loan commitment, which would support uprates at existing plants, reducing financing costs. 20-year Google and Amazon agreements supported more than US$7bn of investment and approximately 1,080MW of added capacity. Existing-site expansion addresses rising power demand, but the financing remains subject to due diligence and definitive documentation, with no funds yet received. (Constellation)
• United Parcel Service upgrades revenue and cash-flow forecasts. United Parcel Service (UPS US) shares rose 5.75% to US$106.09 as Q3 revenue grew 6.7% YoY to US$22.9bn. Adjusted EPS was US$1.69 versus US$1.74; the prior year included a US$0.30 sale-leaseback gain. Annual revenue guidance increased to US$92.6bn from US$91.2bn and free cash flow to US$6.1bn from US$5.5bn. The upgrade supports recovery, with package mix and efficiency still critical. (UPS / Reuters / Market data)
• Royal Caribbean Group raises earnings guidance. Royal Caribbean Group (RCL US) shares rose 5.46% to US$295.92 after Q3 revenue grew about 9% YoY to US$5.59bn and adjusted EPS reached US$6.57 versus US$5.75. Annual adjusted EPS guidance increased to US$17.85–17.95, with 2027 bookings ahead at higher prices. Demand supports the outlook, but expenses deferred into Q4 mean the earnings beat is not entirely a lasting efficiency gain. (Royal Caribbean / Reuters / Market data)
• Pfizer’s Elrexfio clears an efficacy hurdle. Pfizer (PFE US) reported that the 523-patient Phase 3 MagnetisMM-32 trial met its progression-free-survival endpoint in previously treated multiple myeloma, with estimated 18-month progression-free survival of 68%. Pfizer plans regulatory submissions, supporting potential earlier-line use. Overall-survival data remain immature, while grade-three-or-higher infections occurred in 27.5% of Elrexfio patients versus 18.1% of controls; benefit-risk assessment matters before assuming broader adoption. (Pfizer)
• HCA Healthcare faces uninsured-care pressure. HCA Healthcare (HCA US) reported Q3 revenue growth of 3.6% YoY to US$19.85bn and an increase in adjusted EPS of 3.7% to US$7.22. Same-facility admissions grew 2.7%, but increased uninsured care caused an estimated US$400m pretax headwind. Shares fell 3.29% to US$449.96 despite management expecting results in the upper half of annual guidance. Patient volumes support growth, while payer mix remains a profitability risk. (HCA / Market data)
Greater China
• HSBC profit rises, but revenue disappointment weighs on shares. HSBC (0005.HK) reported third-quarter pre-tax profit of US$9.6bn, up 32% YoY, and a buyback of up to US$1bn. Revenue of US$18.6bn missed expectations as wealth growth slowed, Reuters reported. Hong Kong shares fell 5.56% to HK$134.30. Absent prior-year legal provisions of US$1.4bn boosted profit, making recurring revenue momentum the more useful test. (Company / Reuters / Market data) HSBC (0005.HK) is our Core Recommendation.
• Hengrui earnings growth benefits from licensing income. Hengrui Pharma (1276.HK) reported third-quarter revenue of RMB8.95bn, up 20.6% YoY, and attributable profit of RMB2.46bn, up 88.9%, after the market closed. Nine-month innovative-drug sales grew 17.1% to RMB13.87bn, while licensing revenue rose 31.1% to RMB2.78bn. Product growth supports commercial progress, although uneven licensing payments can make quarterly earnings less representative of recurring momentum. (Company / Reuters)
• Meituan secures tighter terms for offshore yuan funding. Meituan (3690.HK) launched RMB8bn of offshore yuan bonds after orders exceeded RMB20bn, Reuters reported. Its five-year tranche yielded 2.50% versus initial guidance of 2.90%, while ten-year pricing tightened to 3.10% from 3.60%. Proceeds will refinance offshore debt. The final terms improve funding flexibility, although strong bond demand does not establish an operating-margin recovery. (Reuters) Meituan (3690.HK) is our Investment Opportunity.
• China profit recovery remains uneven across industries. China’s industrial profits rose 14.4% YoY in September, accelerating from August’s 4.2%. Nine-month profits increased 15.5% to RMB6.03tn. Electronics and communications-equipment profits more than doubled over nine months, while automotive profits fell 22.8%. Official figures show a divergent recovery: aggregate profitability provides limited reassurance for consumer-facing manufacturers facing weak demand and intense competition. (NBS / Reuters)
Asia ex. China
• Korea’s growth accelerates, led by exports and investment. South Korea’s third-quarter GDP expanded 1.0% quarter on quarter, versus 0.6% previously and a 0.7% Reuters poll forecast; growth was 3.4% YoY. Exports rose 2.3% sequentially and facilities investment increased 4.1%, while private consumption fell 0.2%. The Bank of Korea’s estimate shows an export-led recovery, leaving momentum dependent on semiconductor demand rather than consumption. (Bank of Korea / Reuters)
• Canon’s medical supply constraints outweigh stronger quarterly profit. Canon (7751.T) increased third-quarter sales 4.9% YoY to JPY1.159tn and operating profit 10.3% to JPY97.1bn, but cut full-year operating-profit guidance to JPY456bn from JPY465bn. The estimated medical-business sales impact from production constraints doubled to JPY90bn. AI-related component shortages delayed normalisation until next year, illustrating how chip-sector demand can constrain growth for equipment makers. (Company / Investing.com)•
• ST Engineering’s contract wins broaden revenue visibility. ST Engineering (S63.SI) secured S$5.6bn of third-quarter contracts, taking nine-month awards to S$13.2bn. The total excludes a S$1.7bn New Jersey Turnpike contract already included in its order book. The wins span three business segments. Future workloads improve, but the company expects no material current-year earnings impact, making execution and cash conversion the key tests. (Company / The Business Times)
EMEA and Others
• GNovartis lifts its outlook despite pipeline impairments. Novartis (NOVN.SW) raised its full-year core operating-profit outlook to flat to low-single-digit growth in constant currencies from a low-single-digit decline. Third-quarter sales rose 4% YoY to US$14.52bn and core operating profit increased 11% in reported dollars to US$6.04bn. However, US$2.2bn of impairments pushed reported operating profit down 59%, contrasting medicines’ resilience with pipeline investment risk. (Company / Reuters)
• Besi rallies as Applied Materials strengthens its strategic stake. BE Semiconductor Industries (BESI.AS) rose 11.41% to EUR163.05 after acknowledging Applied Materials’ plan for an approximately 20% holding. Their hybrid-bonding partnership supports advanced chip packaging for AI. Applied described the investment as long term and intends no board representation. The reaction signals confidence in the partnership, while execution remains a key investment test. (Company / Market data / Investing.com)
• Mercedes cuts its outlook as China and costs weigh. Mercedes-Benz (MBG.DE) cut its full-year adjusted cars return-on-sales forecast to 2–3% from 3–5%, citing China weakness and material costs. Preliminary third-quarter EBIT of EUR1.77bn beat the company’s EUR1.6bn consensus, but industrial free cash flow of EUR172m missed EUR422m expectations. Weak cash generation makes the outlook cut more consequential than the profit surprise. (Company / dpa via Bernama)
• Reckitt trims growth expectations as volumes remain subdued. Reckitt (RKT.L) lowered full-year core like-for-like revenue growth guidance to 3.5–4.5% from 4–5%. Third-quarter core revenue was GBP2.69bn, up 3.3%, comprising 0.1% volume growth and 3.2% price and mix. North America fell 1.3% as Lysol supply constraints weighed. Limited volume momentum means restoring production and demand matters more than relying on further price increases. (Company / Reuters)
• ASSA ABLOY expands margins despite uneven construction demand. ASSA ABLOY (ASSA-B.ST) reported third-quarter sales of SEK40.77bn, up 6.9% YoY, with organic growth of 4%. Adjusted operating profit increased 11.0% to SEK7.10bn, beating Reuters’ SEK6.94bn consensus, and its margin rose to 17.4% from 16.8%. Americas and EMEIA growth contrasted with an Asian decline; pricing and efficiency support profitability through an uneven construction cycle. (Company / Reuters)
Traders' Corner
Our Technical View
Price further penetrated above its prior peak resistance zone.
The RSI is firmly established in bullish territory and continues to slope upward with strong positive velocity.
This momentum expansion confirms robust underlying trend strength as price approaches its paramount structural pivot at the HK$25.86 all-time high resistance boundary.
A decisive daily close above HK$25.86 will trigger blue-sky price discovery toward higher Fibonacci projection targets.
Our Technical View
Price rebounded off its prior swing-low support zone.
The RSI is rising steadily with positive velocity toward its neutral 50-midline, signaling a progressive recovery in underlying buying power.
As long as price maintains above this defended support floor, we see continued upward expansion toward overhead resistance targets.
Disclosures and disclaimers
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


