Wealth Daily
AI Earnings Doubts Hit Tech As Oil Climbs
Today’s Must-Know News
Overnight Markets
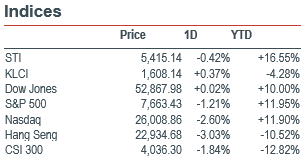
Market Movers: The S&P 500 fell 1.21% and the Nasdaq lost 2.60%. Meta (META US) fell 6.98% in the first cash-session reaction to its results. 3Q revenue rose 26% YoY to US$64.60bn, but operating profit fell 37% to US$12.99bn, including a US$9.89bn legal charge. Its US$135–145bn annual capital-spending outlook keeps funding and returns in focus. Meta also approved a non-voting Class C structure intended to support future funding. The stock dividend depends on the amended charter taking effect in January 2027; it does not yet represent cash raised. Tesla (TSLA US) declined 3.08% after 3Q net profit fell 43% YoY to US$787m; operating margin narrowed to 2.6% from 5.8%. Free cash flow declined 62% YoY to US$1.53bn, highlighting the cash cost of expansion. Lam Research (LRCX US) dropped 11.76% despite September-quarter revenue rising 54.4% YoY to US$8.22bn. These first full-session earnings reactions underline demanding expectations for AI investment and profitability; strong sales alone may not sustain valuations. (Reuters / Meta / Tesla / Lam) Meta (META US) is our Core Recommendation.
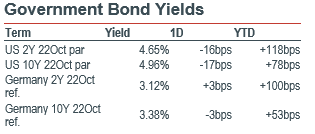
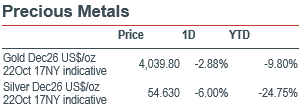
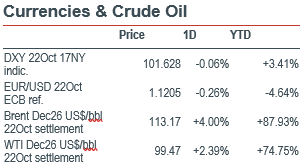
FICC: December Brent rose 4.00% to US$113.17/bbl and WTI gained 2.39% to US$99.47/bbl, amid renewed supply concerns after Houthi attacks on Saudi Arabia. Higher energy costs complicate the inflation outlook. December gold fell 2.88% to US$4,039.80/oz and silver lost 6.00% to US$54.630/oz on matched 17:00 New York indicative snapshots. Separately, the US Treasury 10-year par yield fell 17bps to 4.96% from 5.13%; this official reference differs from an on-the-run closing yield. (Reuters/CNA / Market data / U.S. Treasury)
AI
• AI funding strains eclipse Meta’s growth. Shares fell 6.98% following the previous evening’s results. Revenue rose 26% YoY to US$64.60bn, but free cash flow turned negative US$2.12bn. The proposed non-voting Class C shares provide future financing flexibility; investors face greater scrutiny of cash returns from the US$135–145bn annual capex plan. (Company release / Reuters / Market data) Meta Platforms (META US) is our Core Recommendation.
• Anthropic’s IPO tests selective AI funding. Reuters reported that the model developer still targeted a mid-November listing, while Nscale and Switch delayed their plans. Some investors envisaged a US$1.5tn valuation. The timetable remains tentative and Anthropic declined comment, making financing appetite—not an announced transaction—the immediate signal for the wider AI investment cycle. (Reuters)
• Record chip-equipment sales fail to reassure. Lam (LRCX US) fell 11.76% after the previous evening’s results, amid the wider AI selloff. September-quarter revenue reached US$8.22bn, up 54.4% YoY. December guidance of US$8.6bn, plus or minus US$400m, supports equipment demand, but the selloff highlights sensitivity to customers’ future funding and spending capacity. (Company release / Reuters / Market data)
• Storage earnings reinforce AI infrastructure demand. Western Digital (WDC US) reported fiscal first-quarter revenue of US$4.38bn, up 55% YoY, and adjusted EPS of US$4.64, up 161%. Its December-quarter sales target of US$5.0–5.2bn implies 66–72% YoY growth. Strong pricing and margins support cash generation, while the guidance still requires sustained customer investment. (Company release)
Americas
• Tesla’s profit squeeze challenges its valuation. Tesla (TSLA US) fell 3.08% after the prior evening’s earnings. Third-quarter revenue was broadly flat YoY at US$28.05bn, while net profit fell 43% to US$787m. Capex rose 110% to US$4.73bn and free cash flow declined 62%, leaving execution and returns on expansion central to the investment case. (Company release / Reuters / Market data)
• P&G volumes improve, but costs bite. Procter & Gamble (PG US) rose 5.58% after fiscal first-quarter sales increased 4% YoY to US$23.3bn. Organic volume grew 2.4%, while core EPS edged up 1% to US$2.00. The annual commodity-cost headwind rose to US$1.4bn from US$1bn, making productivity gains important to preserving the unchanged core earnings outlook. (Company release / Reuters / Market data) Procter & Gamble (PG US) is our Core Recommendation.
• Credit opportunities offset weaker exit earnings. Blackstone (BX US) gained 8.38%. Quarterly fee-related earnings rose 6% YoY to US$1.57bn, while net realizations fell 34% to US$332m. Management saw wider credit spreads as an opportunity to earn more on new lending. Recurring fees cushion slower investment exits, but credit selection remains important. (Company release / Reuters / Market data)
• F-35 framework improves long-term visibility. Lockheed (LMT US) rose 6.96% after unveiling a ten-year framework covering 850 U.S. aircraft. Formal awards still require multiyear authority and appropriations. Quarterly sales rose 11% YoY to US$20.71bn, and annual guidance improved. The agreement supports capacity planning, but its proposed volumes are not yet firm orders. (Company release / Company release / Reuters / Market data)
• Clinical progress meets elevated market expectations. Moderna (MRNA US) fell 17.57% as detailed melanoma results emerged. Its vaccine plus Merck’s Keytruda reduced recurrence or death risk by 42% against Keytruda alone in a 1,137-patient trial. Analysts cited profit-taking after a strong rally; overall survival remains immature, limiting conclusions about longer-term clinical benefit. (Company release / Reuters / Market data)
• Rail growth offsets part of the fuel burden. Union Pacific (UNP US) rose 3.55% after revenue increased 15% YoY to US$7.2bn and adjusted EPS grew 15% to US$3.53. Carloads rose 6%, but higher fuel prices hurt the operating ratio by 140bps. Volume and pricing support earnings, while fuel complicates the reported margin trajectory. (Company release / Reuters / Market data)
Greater China
• Alibaba falls in first cash reaction to scrutiny. Alibaba (9988.HK) fell 6.1%, following SAMR’s call for stronger platform product-quality controls. Taotian attended alongside peers. Requirements cover quality oversight, disclosures and after-sales protection, keeping compliance costs in focus; the notice announced no fine or new antitrust penalty against the group. (SAMR / Market data) Alibaba (9988.HK) is our Core Recommendation.
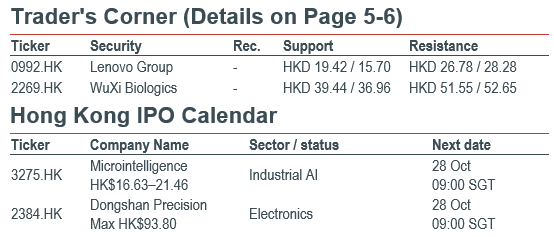
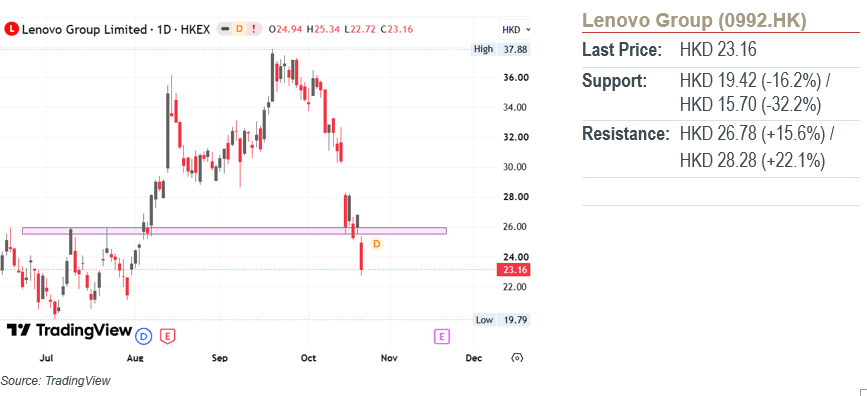
• Lenovo drops as AI funding concerns persist. Lenovo (0992.HK) lost 10.9%. GMT Eight reported a proposed USD2bn refinancing loan at SOFR plus 75bp and Citi’s target-price cut to HKD40 from HKD50, reflecting dilution and valuation changes. Citi described direct exposure to riskier cloud customers as limited; financing access remains an important balance-sheet consideration. (GMT Eight / Market data)
• TSMC explores alternatives to rare-earth components. Reuters reported that TSMC (2330 TW) has surveyed suppliers about rare-earth-free motors for factory automation to reduce exposure to Chinese export controls. Discussions remain preliminary, with no broad rollout, and TSMC declined comment. Taiwan shares had closed 1.4% lower; diversifying critical equipment inputs could strengthen supply resilience for advanced-chip customers. (Reuters / Market data) TSMC (TSM US) is our Core Recommendation.
Asia ex. China
• FCT lifts distributions as property income expands. Frasers Centrepoint Trust (J69U SG) reported FY26 distribution per unit of 12.35 Singapore cents, up 2.0% YoY. Second-half net property income rose 11.5% to SGD160.9mn, while aggregate leverage eased to 38.7% from 40.4% in June. Units gained 2.4%; stronger property earnings and lower leverage improve distribution resilience despite a modest payout increase. (FCT / SGX / Market data)
EMEA and Others
• Nokia’s cash outlook offsets stronger earnings. Nokia’s (NOK US) shares fell 9.7% after 3Q sales rose 10% YoY to EUR5.15bn and comparable operating profit increased 35% to EUR605mn. The company lowered free-cash-flow conversion guidance to 35–55%, citing working capital and accelerated restructuring, while keeping its profit outlook. The divergence puts cash delivery alongside AI network demand in focus. (Nokia / Market data) Nokia (NOK US) is our Investment Opportunity.
• Hermès growth narrows beyond leather goods. Hermès (RMS FP) fell 4.9% after 3Q revenue rose 5.5% YoY to EUR4.10bn, or 4.3% at constant currencies. Leather-goods sales grew 10.8% at constant currencies, but ready-to-wear and accessories declined 2.0%, while Asia excluding Japan was flat. The uneven performance shows that resilient handbags do not yet signal a broad luxury recovery. (Hermès / Market data)
• Nestlé’s volume recovery strengthens, Russia exits accounts. Nestlé (NESN SW) reported 3Q organic sales growth of 4.0% YoY, including 2.8% real internal growth, and retained its 3–4% annual outlook. Deconsolidating its seized Russian business will affect reported sales, operating profit and cash flow from 4Q. Volume improvement supports the turnaround, although the Russia loss reduces reported financial contributions. (Reuters)
• Roche maintains outlook as medicine demand grows. Roche (ROP SW) reported nine-month sales of CHF46.49bn, up 1% YoY in francs and 6% at constant currencies; third-quarter constant-currency growth reached 7%. Stronger pharmaceutical demand offset pressure from Chinese diagnostic pricing reforms. It retained mid-single-digit sales and high-single-digit core EPS growth targets at constant currencies, supporting a steady underlying earnings outlook. (Roche)
• L’Oréal accelerates as beauty demand holds up. L’Oréal (OR FP) reported 3Q sales of EUR11.56bn, up 11.9% YoY. Like-for-like growth was 7.2%, or 7.7% adjusted for IT-transition timing. North Asia grew 7.8% like-for-like, while luxury beauty achieved 7.0% adjusted growth. The broad acceleration supports sales momentum despite an uneven global consumer backdrop and currency effects. (L’Oréal)
• Barclays’ trading mix complicates profit growth. Barclays (BARC LN) reported 3Q pretax profit of GBP2.32bn, up 12% YoY, and announced a GBP500mn buyback. Equities revenue grew 47%, but fixed-income trading fell 19%. Shares declined 2.3%; the split performance leaves execution in rates and credit central to sustaining returns despite the additional capital distribution to shareholders this quarter. (Barclays / Reuters / Market data)
Traders' Corner
Our Technical View
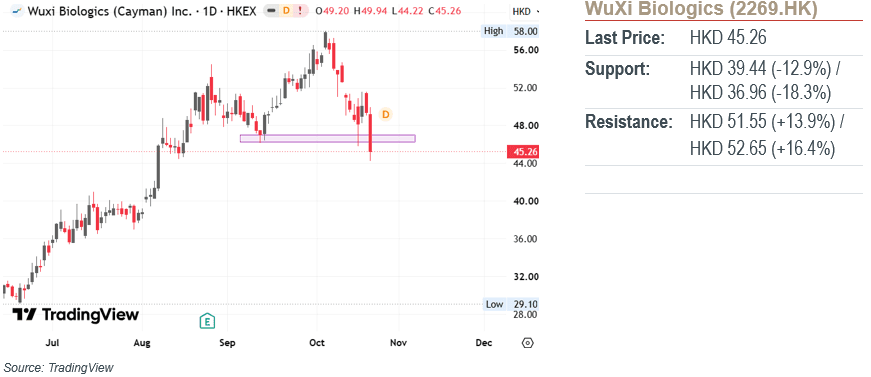
Price violated its prior support zone, invalidating the previous demand floor and confirming a continuation of the broader mark-down sequence.
The RSI is approaching oversold parameters, its sustained bearish alignment and downward trajectory reflect intense sell-side velocity.
As long as price remains capped underneath this newly converted resistance, we see continued downward expansion toward deeper support.
Our Technical View
Price penetrated its prior support baseline and invalidated the established demand floor.
This clean breakdown confirms a downward structural continuation. The RSI remains firmly anchored in bearish territory and continues to slope downward with negative velocity.
As long as price remains capped beneath this newly converted resistance ceiling, we see continued downward expansion toward deeper support
Market Movers: The S&P 500 fell 1.21% and the Nasdaq lost 2.60%. Meta (META US) fell 6.98% in the first cash-session reaction to its results. 3Q revenue rose 26% YoY to US$64.60bn, but operating profit fell 37% to US$12.99bn, including a US$9.89bn legal charge. Its US$135–145bn annual capital-spending outlook keeps funding and returns in focus. Meta also approved a non-voting Class C structure intended to support future funding. The stock dividend depends on the amended charter taking effect in January 2027; it does not yet represent cash raised. Tesla (TSLA US) declined 3.08% after 3Q net profit fell 43% YoY to US$787m; operating margin narrowed to 2.6% from 5.8%. Free cash flow declined 62% YoY to US$1.53bn, highlighting the cash cost of expansion. Lam Research (LRCX US) dropped 11.76% despite September-quarter revenue rising 54.4% YoY to US$8.22bn. These first full-session earnings reactions underline demanding expectations for AI investment and profitability; strong sales alone may not sustain valuations. (Reuters / Meta / Tesla / Lam) Meta (META US) is our Core Recommendation.
FICC: December Brent rose 4.00% to US$113.17/bbl and WTI gained 2.39% to US$99.47/bbl, amid renewed supply concerns after Houthi attacks on Saudi Arabia. Higher energy costs complicate the inflation outlook. December gold fell 2.88% to US$4,039.80/oz and silver lost 6.00% to US$54.630/oz on matched 17:00 New York indicative snapshots. Separately, the US Treasury 10-year par yield fell 17bps to 4.96% from 5.13%; this official reference differs from an on-the-run closing yield. (Reuters/CNA / Market data / U.S. Treasury)
AI
• AI funding strains eclipse Meta’s growth. Shares fell 6.98% following the previous evening’s results. Revenue rose 26% YoY to US$64.60bn, but free cash flow turned negative US$2.12bn. The proposed non-voting Class C shares provide future financing flexibility; investors face greater scrutiny of cash returns from the US$135–145bn annual capex plan. (Company release / Reuters / Market data) Meta Platforms (META US) is our Core Recommendation.
• Anthropic’s IPO tests selective AI funding. Reuters reported that the model developer still targeted a mid-November listing, while Nscale and Switch delayed their plans. Some investors envisaged a US$1.5tn valuation. The timetable remains tentative and Anthropic declined comment, making financing appetite—not an announced transaction—the immediate signal for the wider AI investment cycle. (Reuters)
• Record chip-equipment sales fail to reassure. Lam (LRCX US) fell 11.76% after the previous evening’s results, amid the wider AI selloff. September-quarter revenue reached US$8.22bn, up 54.4% YoY. December guidance of US$8.6bn, plus or minus US$400m, supports equipment demand, but the selloff highlights sensitivity to customers’ future funding and spending capacity. (Company release / Reuters / Market data)
• Storage earnings reinforce AI infrastructure demand. Western Digital (WDC US) reported fiscal first-quarter revenue of US$4.38bn, up 55% YoY, and adjusted EPS of US$4.64, up 161%. Its December-quarter sales target of US$5.0–5.2bn implies 66–72% YoY growth. Strong pricing and margins support cash generation, while the guidance still requires sustained customer investment. (Company release)
Americas
• Tesla’s profit squeeze challenges its valuation. Tesla (TSLA US) fell 3.08% after the prior evening’s earnings. Third-quarter revenue was broadly flat YoY at US$28.05bn, while net profit fell 43% to US$787m. Capex rose 110% to US$4.73bn and free cash flow declined 62%, leaving execution and returns on expansion central to the investment case. (Company release / Reuters / Market data)
• P&G volumes improve, but costs bite. Procter & Gamble (PG US) rose 5.58% after fiscal first-quarter sales increased 4% YoY to US$23.3bn. Organic volume grew 2.4%, while core EPS edged up 1% to US$2.00. The annual commodity-cost headwind rose to US$1.4bn from US$1bn, making productivity gains important to preserving the unchanged core earnings outlook. (Company release / Reuters / Market data) Procter & Gamble (PG US) is our Core Recommendation.
• Credit opportunities offset weaker exit earnings. Blackstone (BX US) gained 8.38%. Quarterly fee-related earnings rose 6% YoY to US$1.57bn, while net realizations fell 34% to US$332m. Management saw wider credit spreads as an opportunity to earn more on new lending. Recurring fees cushion slower investment exits, but credit selection remains important. (Company release / Reuters / Market data)
• F-35 framework improves long-term visibility. Lockheed (LMT US) rose 6.96% after unveiling a ten-year framework covering 850 U.S. aircraft. Formal awards still require multiyear authority and appropriations. Quarterly sales rose 11% YoY to US$20.71bn, and annual guidance improved. The agreement supports capacity planning, but its proposed volumes are not yet firm orders. (Company release / Company release / Reuters / Market data)
• Clinical progress meets elevated market expectations. Moderna (MRNA US) fell 17.57% as detailed melanoma results emerged. Its vaccine plus Merck’s Keytruda reduced recurrence or death risk by 42% against Keytruda alone in a 1,137-patient trial. Analysts cited profit-taking after a strong rally; overall survival remains immature, limiting conclusions about longer-term clinical benefit. (Company release / Reuters / Market data)
• Rail growth offsets part of the fuel burden. Union Pacific (UNP US) rose 3.55% after revenue increased 15% YoY to US$7.2bn and adjusted EPS grew 15% to US$3.53. Carloads rose 6%, but higher fuel prices hurt the operating ratio by 140bps. Volume and pricing support earnings, while fuel complicates the reported margin trajectory. (Company release / Reuters / Market data)
Greater China
• Alibaba falls in first cash reaction to scrutiny. Alibaba (9988.HK) fell 6.1%, following SAMR’s call for stronger platform product-quality controls. Taotian attended alongside peers. Requirements cover quality oversight, disclosures and after-sales protection, keeping compliance costs in focus; the notice announced no fine or new antitrust penalty against the group. (SAMR / Market data) Alibaba (9988.HK) is our Core Recommendation.
• Lenovo drops as AI funding concerns persist. Lenovo (0992.HK) lost 10.9%. GMT Eight reported a proposed USD2bn refinancing loan at SOFR plus 75bp and Citi’s target-price cut to HKD40 from HKD50, reflecting dilution and valuation changes. Citi described direct exposure to riskier cloud customers as limited; financing access remains an important balance-sheet consideration. (GMT Eight / Market data)
• TSMC explores alternatives to rare-earth components. Reuters reported that TSMC (2330 TW) has surveyed suppliers about rare-earth-free motors for factory automation to reduce exposure to Chinese export controls. Discussions remain preliminary, with no broad rollout, and TSMC declined comment. Taiwan shares had closed 1.4% lower; diversifying critical equipment inputs could strengthen supply resilience for advanced-chip customers. (Reuters / Market data) TSMC (TSM US) is our Core Recommendation.
Asia ex. China
• FCT lifts distributions as property income expands. Frasers Centrepoint Trust (J69U SG) reported FY26 distribution per unit of 12.35 Singapore cents, up 2.0% YoY. Second-half net property income rose 11.5% to SGD160.9mn, while aggregate leverage eased to 38.7% from 40.4% in June. Units gained 2.4%; stronger property earnings and lower leverage improve distribution resilience despite a modest payout increase. (FCT / SGX / Market data)
EMEA and Others
• Nokia’s cash outlook offsets stronger earnings. Nokia’s (NOK US) shares fell 9.7% after 3Q sales rose 10% YoY to EUR5.15bn and comparable operating profit increased 35% to EUR605mn. The company lowered free-cash-flow conversion guidance to 35–55%, citing working capital and accelerated restructuring, while keeping its profit outlook. The divergence puts cash delivery alongside AI network demand in focus. (Nokia / Market data) Nokia (NOK US) is our Investment Opportunity.
• Hermès growth narrows beyond leather goods. Hermès (RMS FP) fell 4.9% after 3Q revenue rose 5.5% YoY to EUR4.10bn, or 4.3% at constant currencies. Leather-goods sales grew 10.8% at constant currencies, but ready-to-wear and accessories declined 2.0%, while Asia excluding Japan was flat. The uneven performance shows that resilient handbags do not yet signal a broad luxury recovery. (Hermès / Market data)
• Nestlé’s volume recovery strengthens, Russia exits accounts. Nestlé (NESN SW) reported 3Q organic sales growth of 4.0% YoY, including 2.8% real internal growth, and retained its 3–4% annual outlook. Deconsolidating its seized Russian business will affect reported sales, operating profit and cash flow from 4Q. Volume improvement supports the turnaround, although the Russia loss reduces reported financial contributions. (Reuters)
• Roche maintains outlook as medicine demand grows. Roche (ROP SW) reported nine-month sales of CHF46.49bn, up 1% YoY in francs and 6% at constant currencies; third-quarter constant-currency growth reached 7%. Stronger pharmaceutical demand offset pressure from Chinese diagnostic pricing reforms. It retained mid-single-digit sales and high-single-digit core EPS growth targets at constant currencies, supporting a steady underlying earnings outlook. (Roche)
• L’Oréal accelerates as beauty demand holds up. L’Oréal (OR FP) reported 3Q sales of EUR11.56bn, up 11.9% YoY. Like-for-like growth was 7.2%, or 7.7% adjusted for IT-transition timing. North Asia grew 7.8% like-for-like, while luxury beauty achieved 7.0% adjusted growth. The broad acceleration supports sales momentum despite an uneven global consumer backdrop and currency effects. (L’Oréal)
• Barclays’ trading mix complicates profit growth. Barclays (BARC LN) reported 3Q pretax profit of GBP2.32bn, up 12% YoY, and announced a GBP500mn buyback. Equities revenue grew 47%, but fixed-income trading fell 19%. Shares declined 2.3%; the split performance leaves execution in rates and credit central to sustaining returns despite the additional capital distribution to shareholders this quarter. (Barclays / Reuters / Market data)
Traders' Corner
Our Technical View
Price violated its prior support zone, invalidating the previous demand floor and confirming a continuation of the broader mark-down sequence.
The RSI is approaching oversold parameters, its sustained bearish alignment and downward trajectory reflect intense sell-side velocity.
As long as price remains capped underneath this newly converted resistance, we see continued downward expansion toward deeper support.
Our Technical View
Price penetrated its prior support baseline and invalidated the established demand floor.
This clean breakdown confirms a downward structural continuation. The RSI remains firmly anchored in bearish territory and continues to slope downward with negative velocity.
As long as price remains capped beneath this newly converted resistance ceiling, we see continued downward expansion toward deeper support
Disclosures and disclaimers
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


