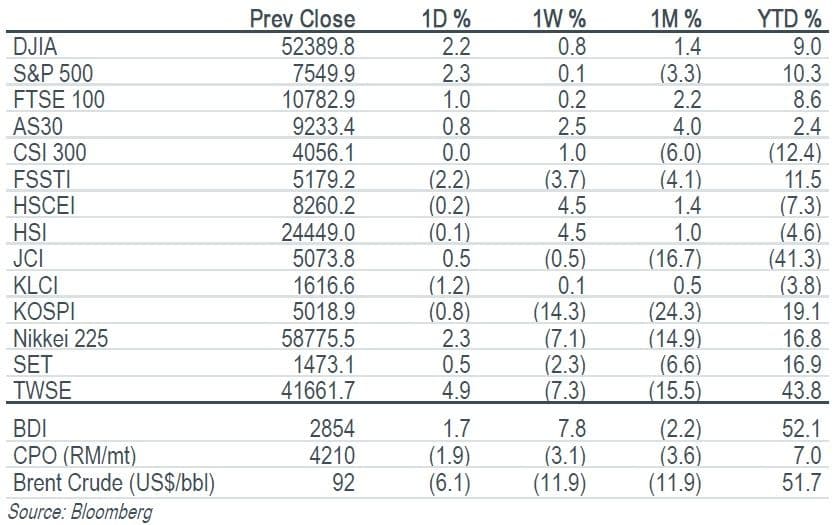
Key Indices
Top Stories
Company Results | Central Pattana (CPN TB/BUY/Bt65.75/Target: Bt80.00)
- CPN reported a 3Q26 core profit of Bt4.83b (+15% yoy, +4% qoq), in line with our and consensus expectations. Gross margin increased 60bp yoy, while SG&A-to-revenue was broadly stable yoy. The 10-year Thai government bond yield has declined since early-Oct 26 to 2.05%, making high dividend yield stocks such as CPN more attractive. Maintain BUY with a SOTP-based target price of Bt80.00.
Company Results | Dohome (DOHOME TB/BUY/Bt3.50/Target: Bt4.50)
- DOHOME reported a 3Q26 net profit of Bt112m, up by 10% yoy but down by 63% qoq, in line with our expectations and 9% below consensus estimates. We are more positive on its 4Q26 outlook and preliminarily expect double - digit yoy earnings growth, supported by positive SSSG and gross margin improvement. Maintain BUY with a target price of Bt4.50.
Company Results | Indorama Ventures (IVL TB/BUY/Bt22.30/Target: Bt28.00)
- IVL reported a 3Q26 net profit of Bt2.2b, reversing the loss in 3Q25 but declining 64% qoq, mainly due to weaker PET spreads. We expect earnings to improve in 2027, supported by structural cost savings, fibres recovery and EPL consolidation in 1Q27. We raise our 2027 earnings forecast by 5%, with further upside from potential asset disposals and lower financing costs. Maintain BUY with a target price of Bt28.00, reflecting improving earnings visibility.
Company Results | IRPC (IRPC TB/BUY/Bt2.40/Target: Bt3.00)
- We upgrade IRPC to BUY, maintaining our target price of Bt3.00, following a 25% share price correction from its September peak. Although the 3Q26 net profit of Bt4.55b missed our forecast, core earnings remained broadly in line with expectations, supported by strong refining margins. We expect 4Q26 earnings to soften due to lower refinery utilisation and higher crude procurement costs. Nevertheless, resilient diesel cracks and a potential petrochemical margin improvement underpin our 2027 recovery outlook, offering an attractive 25% upside.
Top Stories
Company Results | Central Pattana (CPN TB/BUY/Bt65.75/Target: Bt80.00)
- CPN reported a 3Q26 core profit of Bt4.83b (+15% yoy, +4% qoq), in line with our and consensus expectations. Gross margin increased 60bp yoy, while SG&A-to-revenue was broadly stable yoy. The 10-year Thai government bond yield has declined since early-Oct 26 to 2.05%, making high dividend yield stocks such as CPN more attractive. Maintain BUY with a SOTP-based target price of Bt80.00.
Company Results | Dohome (DOHOME TB/BUY/Bt3.50/Target: Bt4.50)
- DOHOME reported a 3Q26 net profit of Bt112m, up by 10% yoy but down by 63% qoq, in line with our expectations and 9% below consensus estimates. We are more positive on its 4Q26 outlook and preliminarily expect double - digit yoy earnings growth, supported by positive SSSG and gross margin improvement. Maintain BUY with a target price of Bt4.50.
Company Results | Indorama Ventures (IVL TB/BUY/Bt22.30/Target: Bt28.00)
- IVL reported a 3Q26 net profit of Bt2.2b, reversing the loss in 3Q25 but declining 64% qoq, mainly due to weaker PET spreads. We expect earnings to improve in 2027, supported by structural cost savings, fibres recovery and EPL consolidation in 1Q27. We raise our 2027 earnings forecast by 5%, with further upside from potential asset disposals and lower financing costs. Maintain BUY with a target price of Bt28.00, reflecting improving earnings visibility.
Company Results | IRPC (IRPC TB/BUY/Bt2.40/Target: Bt3.00)
- We upgrade IRPC to BUY, maintaining our target price of Bt3.00, following a 25% share price correction from its September peak. Although the 3Q26 net profit of Bt4.55b missed our forecast, core earnings remained broadly in line with expectations, supported by strong refining margins. We expect 4Q26 earnings to soften due to lower refinery utilisation and higher crude procurement costs. Nevertheless, resilient diesel cracks and a potential petrochemical margin improvement underpin our 2027 recovery outlook, offering an attractive 25% upside.
Key Indices
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


