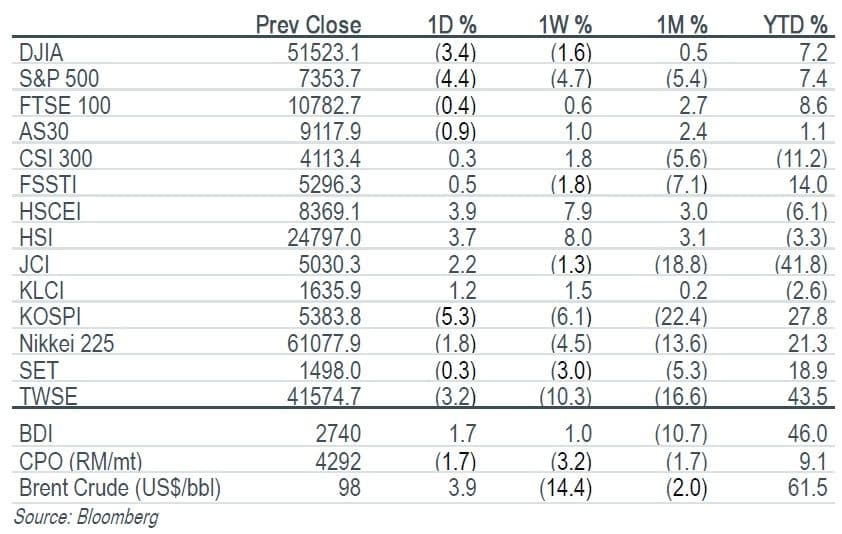
Key Indices
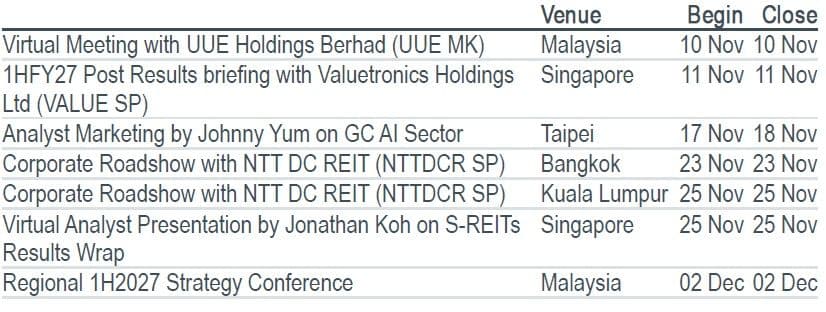
Top Stories
Company Results | Bangchak Corporation (BCP TB/BUY/Bt43.50/Target: Bt65.00)
- BCP reported 3Q26 net profit of Bt9.85b (-20% qoq), while core profit rose 287% yoy and 1% qoq to Bt12.3b, in line with our forecast. Strong refining margins (US$17.36/bbl) were partly offset by higher hedging losses and lower refinery utilisation. We expect 4Q26 earnings to soften qoq as GRM normalises, despite recovering throughput. Looking ahead, resilient diesel cracks, full-year SAF contributions and diversified earnings should support profitability in 2027. Maintain BUY with a target price of Bt65.00.
Company Update | CH. Karnchang (CK TB/BUY/Bt17.80/Target: Bt28.00)
- We expect CK to report a 3Q26 net profit of Bt1.26b (-27% yoy, +58% qoq). Construction revenue should reach Bt11.4b (+4% yoy) with gross margin at 7.7%. Meanwhile, the share of profit from associates is expected to rise 48% qoq to Bt692m, supported by stronger contributions from BEM and CKP. Earnings should also benefit from a one-off gain of approximately Bt300m before tax from the sale of BEM shares. We maintain BUY with a higher target price of Bt28.00.
Company Update | PTT (PTT TB/BUY/Bt38.50/Target: Bt48.00)
- We expect 3Q26 net profit to decline qoq due to seasonal factors, driven by lower gas demand and reduced sales volumes from the gas separation business following the maintenance shutdown of GSP unit 6. Meanwhile, the Genesis project continues to progress, although slightly behind the original schedule. PTT expects to finalise the project’s details within 4Q26. We forecast a 2026 dividend of Bt3.00/share. Maintain BUY; target price: Bt48.00 (previously Bt45.00).
Company Update | Stecon Group (STECON TB/BUY/Bt18.20/Target: Bt22.00)
- We expect STECON to report a 3Q26 net profit of Bt281m (+72% yoy, -69% qoq), supported by stronger construction revenue, while the qoq decline reflects the absence of dividend income. Construction revenue should rise 33% yoy and 6% qoq, driven by progress in ongoing projects. Gross margin is expected to remain above 7%. Looking ahead, DC opportunities could support new contract awards and earnings visibility from 2027 onwards. Maintain BUY with an unchanged target price of Bt22.00.
What’s Inside
Company Results | PTT Oil and Retail (OR TB/HOLD/Bt12.60/Target: Bt12.50)
- OR reported a 3Q26 net profit of Bt5.14b, recovering from a net loss in 2Q26. The result was in line with our estimate but 75% above consensus, driven by a strong qoq recovery in the mobility business. Looking ahead, we expect 4Q26 net profit to decline qoq as the marketing margin normalises. We believe uncertainty surrounding the investment review will remain an overhang on OR’s share price until greater clarity emerges. Maintain HOLD. Target price: Bt12.50.
Top Stories
Company Results | Bangchak Corporation (BCP TB/BUY/Bt43.50/Target: Bt65.00)
- BCP reported 3Q26 net profit of Bt9.85b (-20% qoq), while core profit rose 287% yoy and 1% qoq to Bt12.3b, in line with our forecast. Strong refining margins (US$17.36/bbl) were partly offset by higher hedging losses and lower refinery utilisation. We expect 4Q26 earnings to soften qoq as GRM normalises, despite recovering throughput. Looking ahead, resilient diesel cracks, full-year SAF contributions and diversified earnings should support profitability in 2027. Maintain BUY with a target price of Bt65.00.
Company Update | CH. Karnchang (CK TB/BUY/Bt17.80/Target: Bt28.00)
- We expect CK to report a 3Q26 net profit of Bt1.26b (-27% yoy, +58% qoq). Construction revenue should reach Bt11.4b (+4% yoy) with gross margin at 7.7%. Meanwhile, the share of profit from associates is expected to rise 48% qoq to Bt692m, supported by stronger contributions from BEM and CKP. Earnings should also benefit from a one-off gain of approximately Bt300m before tax from the sale of BEM shares. We maintain BUY with a higher target price of Bt28.00.
Company Update | PTT (PTT TB/BUY/Bt38.50/Target: Bt48.00)
- We expect 3Q26 net profit to decline qoq due to seasonal factors, driven by lower gas demand and reduced sales volumes from the gas separation business following the maintenance shutdown of GSP unit 6. Meanwhile, the Genesis project continues to progress, although slightly behind the original schedule. PTT expects to finalise the project’s details within 4Q26. We forecast a 2026 dividend of Bt3.00/share. Maintain BUY; target price: Bt48.00 (previously Bt45.00).
Company Update | Stecon Group (STECON TB/BUY/Bt18.20/Target: Bt22.00)
- We expect STECON to report a 3Q26 net profit of Bt281m (+72% yoy, -69% qoq), supported by stronger construction revenue, while the qoq decline reflects the absence of dividend income. Construction revenue should rise 33% yoy and 6% qoq, driven by progress in ongoing projects. Gross margin is expected to remain above 7%. Looking ahead, DC opportunities could support new contract awards and earnings visibility from 2027 onwards. Maintain BUY with an unchanged target price of Bt22.00.
What’s Inside
Company Results | PTT Oil and Retail (OR TB/HOLD/Bt12.60/Target: Bt12.50)
- OR reported a 3Q26 net profit of Bt5.14b, recovering from a net loss in 2Q26. The result was in line with our estimate but 75% above consensus, driven by a strong qoq recovery in the mobility business. Looking ahead, we expect 4Q26 net profit to decline qoq as the marketing margin normalises. We believe uncertainty surrounding the investment review will remain an overhang on OR’s share price until greater clarity emerges. Maintain HOLD. Target price: Bt12.50.
Key Indices
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


