

Company Coverage
HANA (Thailand) (HANA TB): Earnings Expected To Recover, While AI-Related Mass Production Starts In 3Q26
BUY (Maintained)
Current price:
Target price:
Upside:
Bt47.50
Bt56.00
17.9%
Analyst
Analyst
Sirithat Prasertwuti
Highlights
- We expect HANA to report a 3Q26 core profit of Bt303m (+697% yoy, +9% qoq), continuing its earnings recovery.
- Earnings recovery in 2H26 should be driven by narrowing losses at PMS, higher IC utilisation rates and resilient PCBA sales.
- HANA entered mass production for two AI-related projects in 3Q26, including solid-state cooling and high-density PCBA.
- Maintain BUY with a higher target price of Bt56.00, backed by a 37% earnings CAGR in 2025-28 and continued operational improvements at PMS in 2H26.
Analysis
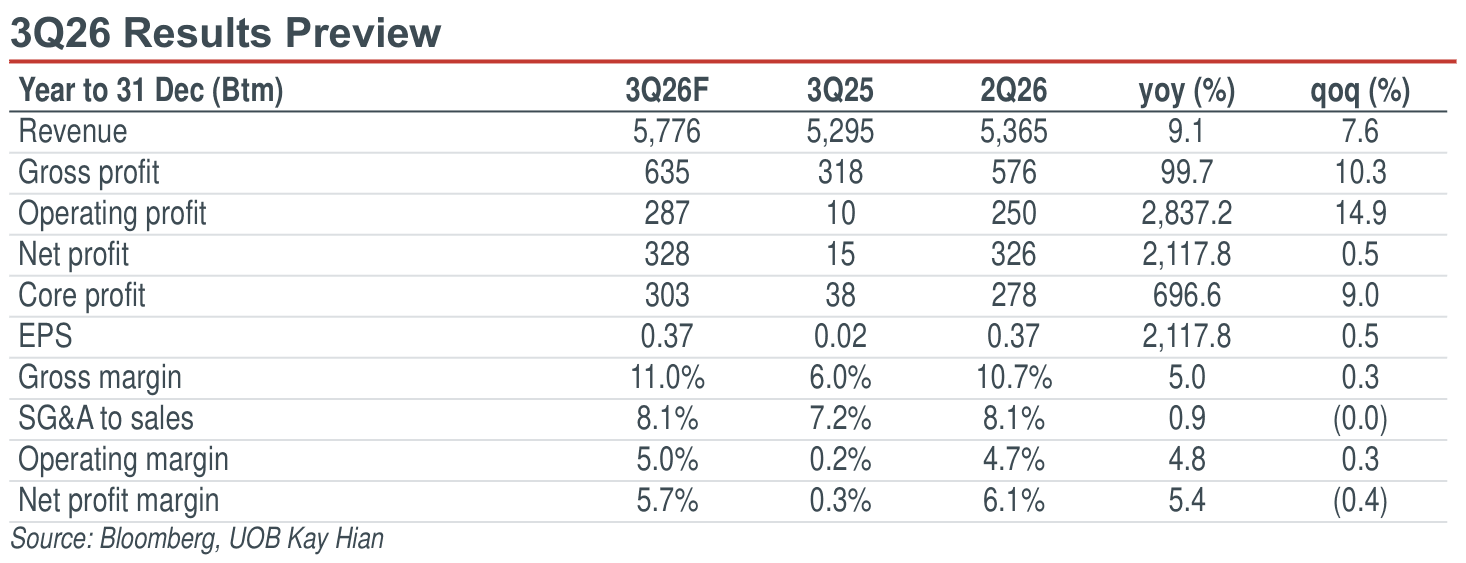
- 3Q26 earnings are expected to remain on a recovery path, mainly driven by narrower losses at PMS, while PCBA and IC operations should continue to improve in 2H26. We project that HANA (Thailand) (HANA) will report a core net profit of Bt303m (+697% yoy, +9% qoq), supported by higher sales and improving margins. We forecast revenue of Bt5.78b (+9% yoy, +8% qoq), driven by resilient printed circuit board assembly (PCBA) sales and improving integrated circuit (IC) sales, supported by higher utilisation rates in 2H26. We expect gross margin to continue recovering to 11.0% in 3Q26 (vs 9.5% in 1H26 and 10.7% in 2Q26), mainly driven by continued operational improvements at Power Master Semiconductor Co (PMS). Although PMS could remain loss-making in 2026, we expect its losses to continue narrowing in 2H26, supported by HANA's efforts to strengthen its operations in Korea and expand its presence in China, where marketing efforts have begun to deliver results since 2Q26. This includes cooperation with a Chinese foundry to penetrate China's silicon carbide market.
Highlights
- We expect HANA to report a 3Q26 core profit of Bt303m (+697% yoy, +9% qoq), continuing its earnings recovery.
- Earnings recovery in 2H26 should be driven by narrowing losses at PMS, higher IC utilisation rates and resilient PCBA sales.
- HANA entered mass production for two AI-related projects in 3Q26, including solid-state cooling and high-density PCBA.
- Maintain BUY with a higher target price of Bt56.00, backed by a 37% earnings CAGR in 2025-28 and continued operational improvements at PMS in 2H26.
Analysis
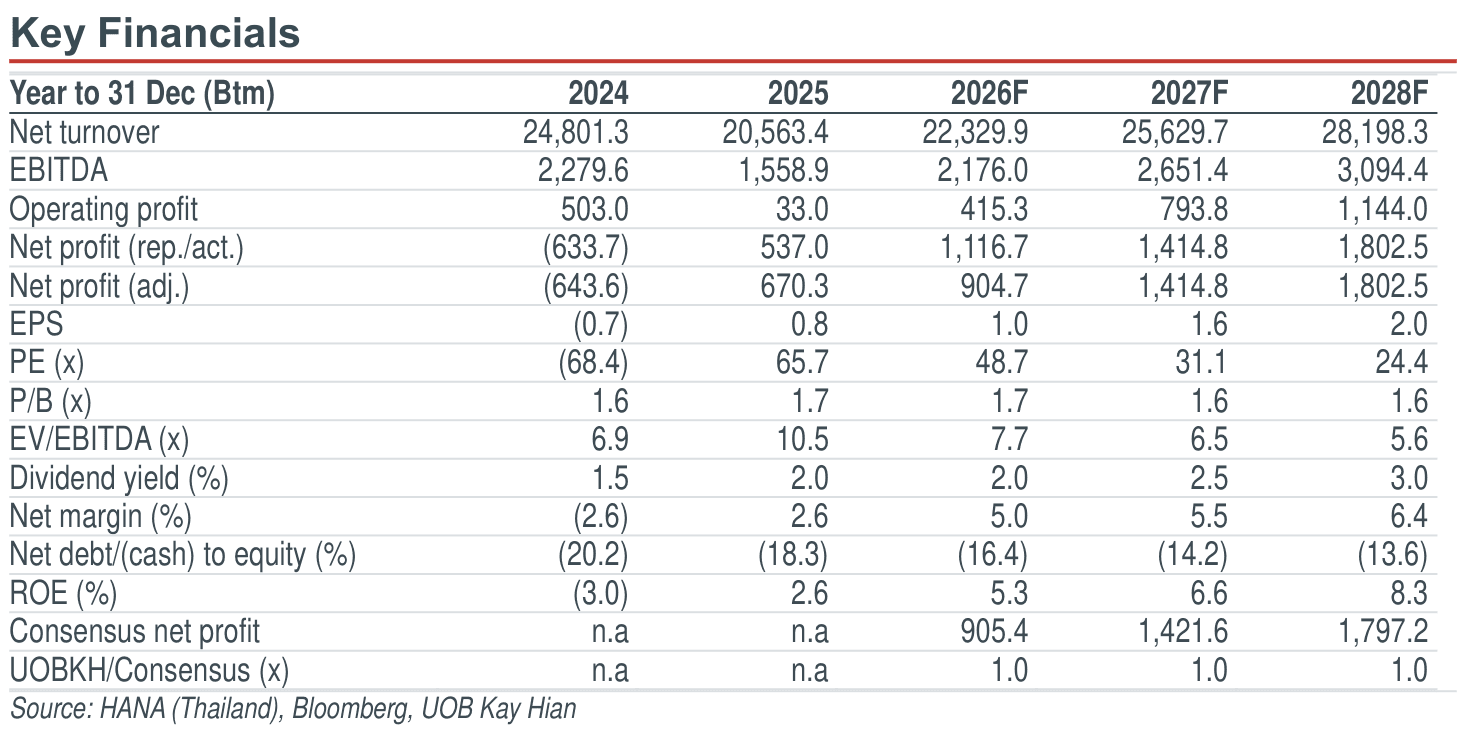
- 3Q26 earnings are expected to remain on a recovery path, mainly driven by narrower losses at PMS, while PCBA and IC operations should continue to improve in 2H26. We project that HANA (Thailand) (HANA) will report a core net profit of Bt303m (+697% yoy, +9% qoq), supported by higher sales and improving margins. We forecast revenue of Bt5.78b (+9% yoy, +8% qoq), driven by resilient printed circuit board assembly (PCBA) sales and improving integrated circuit (IC) sales, supported by higher utilisation rates in 2H26. We expect gross margin to continue recovering to 11.0% in 3Q26 (vs 9.5% in 1H26 and 10.7% in 2Q26), mainly driven by continued operational improvements at Power Master Semiconductor Co (PMS). Although PMS could remain loss-making in 2026, we expect its losses to continue narrowing in 2H26, supported by HANA's efforts to strengthen its operations in Korea and expand its presence in China, where marketing efforts have begun to deliver results since 2Q26. This includes cooperation with a Chinese foundry to penetrate China's silicon carbide market.
BUY (Maintained)
Current price:
Target price:
Upside:
Bt47.50
Bt56.00
17.9%
Analyst
Analyst
Sirithat Prasertwuti
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

28 Sept 2026
Delta (Thailand) (DELTA TB) : 3Q26 Results Preview: Earnings Expected To Improve qoq, Driven By Higher Sales And Margins

19 Oct 2026
COM7 (COM7 TB): Earnings Expected To Surge In 3Q26

21 Oct 2026


